Buying waterfront
Canal-front and Gulf-access purchases, appraisals, seawalls and docks.
Cape Coral · Lee County, FL
Buying a Gulf-access home on a saltwater canal, buying a freshwater canal home inland, and building new on one of the city’s thousands of vacant lots are not variations on one conversation. They are separate loans with separate rules.
We handle all three. Start with the one you are in.
Voted Best Mortgage Broker in Cape Coral · Best of Cape Coral 2026
Canal-front and Gulf-access purchases, appraisals, seawalls and docks.
Construction-to-permanent financing, lot and builder review, draw schedules.
Conventional, FHA, VA, investor programs, and refinance analysis.
Path 01
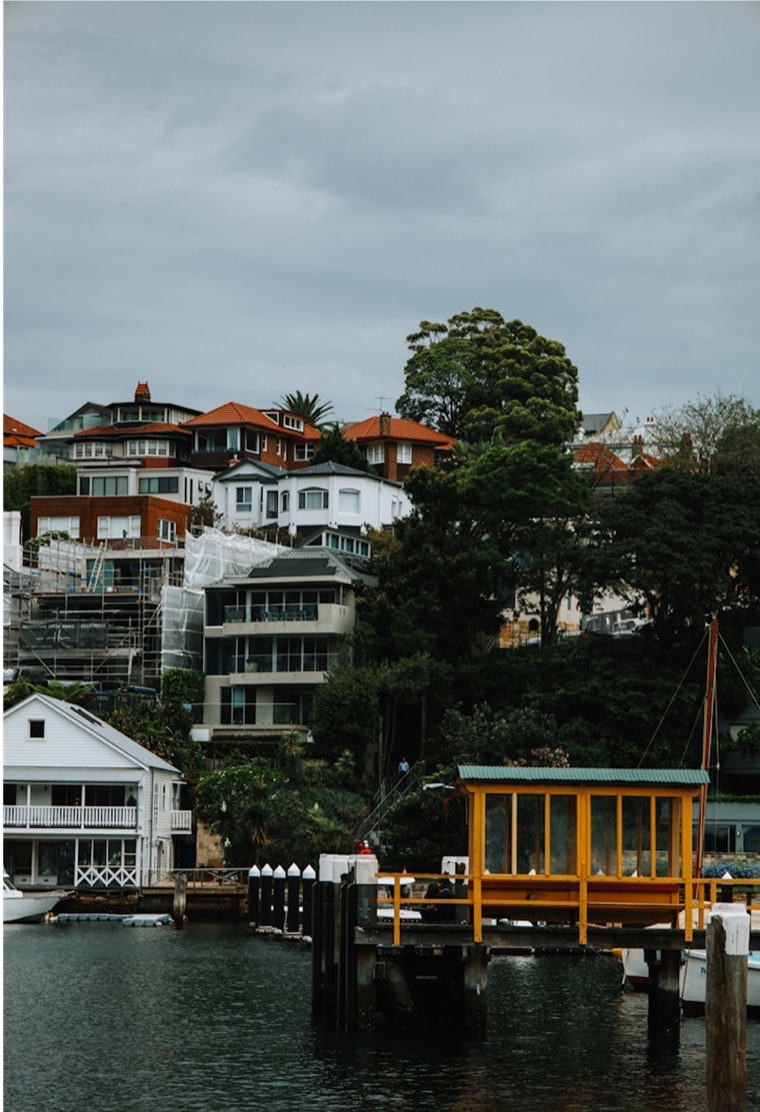
Over 400 miles of canals, and not all of them reach the Gulf.
A waterfront purchase is underwritten on things a standard inland file never raises. Four of them decide most deals.
Whether a boat can reach the Gulf without a lift-out changes the value of an otherwise identical house, and the most common appraisal problem here is comparables pulled from freshwater or off-water streets. It is a real difference in price that a form cannot see, which is why the appraisal is not a formality on a waterfront purchase.
These are real value and also real underwriting items. A deteriorating seawall can come back as a required repair, particularly on FHA and VA loans where property-condition standards are stricter. If you are buying a home with an older seawall, budget for the inspection.
For buyers whose boat is part of the reason they are buying, bridge clearance sets what the property is worth to them — and it also constrains the comparable set an appraiser is allowed to use. Worth confirming before you settle on an offer price. You can check bridge clearances and time to the Gulf for a specific address before you write.
Waterfront property in Lee County means a flood zone determination, often an elevation certificate, and wind coverage. Premiums vary sharply between two houses that look alike, and because insurance is part of your monthly payment it directly affects what you qualify for. Shop it the week you go under contract, not the week before closing.
Path 02
An unusual amount of vacant residential land sits inside the city limits, which is why Cape Coral has so much new construction.
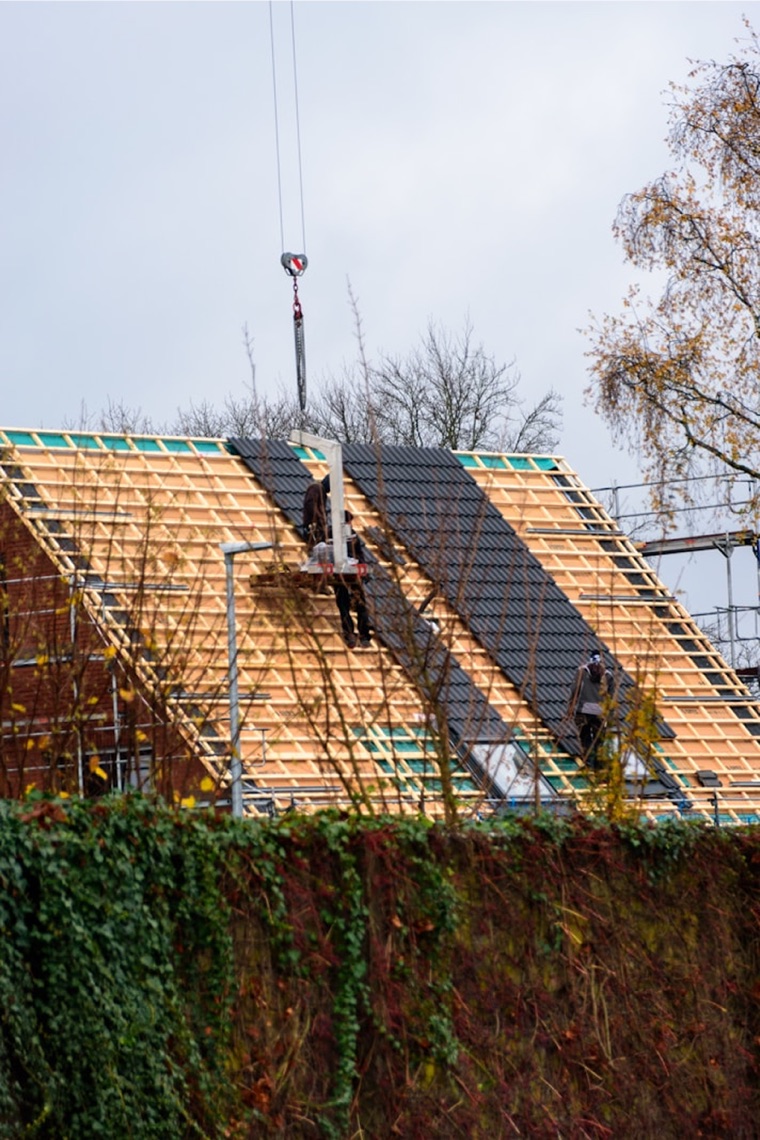
Financing a build works differently from buying a finished house: the money is released in stages as the work is inspected, and the loan is sized against what the finished home will be worth rather than what you paid for the land. Handled well, it converts into your permanent mortgage without a second closing.
How the process actually runs
Ideally before you buy the lot. This establishes the total project cost you can support — which matters more than usual here, because your loan amount is based on the completed appraised value, not the land price.
Lenders underwrite your builder, not just you: licence, insurance, financials and track record. If you have chosen a builder who cannot clear that review, you want to know before you sign a contract.
An appraiser values a house that does not exist yet, working from your plans and comparable finished homes. That number sets your maximum loan amount.
You close before construction starts. The loan then funds in stages as work is completed — typically foundation, framing, dry-in, mechanicals, drywall, completion — each requiring an inspection. You pay interest only on what has been drawn, so payments start small and grow as the building progresses.
On completion and final inspection the loan converts to your permanent mortgage at pre-agreed terms. No second closing, no second set of costs.
Not every Cape Coral lot is connected to city water and sewer. If yours is not, and utilities are being brought down the street, there may be an assessment attached to the property; an unconnected lot needs well and septic instead, which adds cost, adds permitting time, and affects the appraisal. Confirm connection status with the city before you buy a lot, not after.
These belong in the budget from day one. Build timelines in Lee County have run long during high-demand periods, and a construction loan has a term. Extensions are usually possible, but they are not free.
Build a contingency — lenders generally require one — and if yours is not funded, the overage comes out of your pocket at exactly the moment you have the least flexibility.
Path 03
Buying existing, or refinancing.
The most common path, and the one where the monthly number decides everything. Before the program question is worth asking, work out what the house actually costs to hold. The Lee County Property Appraiser publishes assessed values, tax history and ownership records for every address in the county — worth checking on anything you are serious about.
Cost of carry
Waterfront and inland property can carry very differently at the same purchase price, because flood zone, elevation and wind exposure all land on the insurance line. Change that one figure and watch the payment move.
Assumptions — edit any of these
Estimated monthly cost to hold
$3,820/mo
28% of this payment is not loan repayment. $1,061 a month goes to taxes, insurance and dues, and lenders count all of it against your debt-to-income ratio — so it changes what you can borrow, not just what you pay.
This is an illustration, not an offer. Figures are built from the assumptions above; your own rate, taxes, insurance premium and any assessments will differ. Mortgage insurance, flood insurance and closing costs are not included.
The insurance default above is set for an inland Cape Coral house. A Gulf-access property in a flood zone can run materially higher once flood and wind are added, which is the single figure most worth replacing with a real quote before you rely on this number.
As little as 3% down for qualified first-time buyers, 5% otherwise. Mortgage insurance drops off once you reach sufficient equity — the main structural advantage over FHA.
A lower down payment and more forgiving credit guidelines, within the county loan limit.
Eligible veterans and service members buy with zero down, no monthly mortgage insurance and competitive rates. Lee County has a substantial veteran population and this is underused.
Cape Coral is a working vacation-rental market. DSCR loans qualify on the property’s rental income instead of your personal income, which is often the difference between a deal working and not. More on DSCR.
Finance a purchase plus the work in a single loan, rather than buying first and paying for the work later out of pocket.
Lower your rate or payment, shorten your term, pull out equity, or drop mortgage insurance. We will show you the break-even before you commit, including when it says stay put. Start a refinance.
Qualify on deposits rather than tax returns. Built for self-employed borrowers whose returns understate what the business actually earns, which is a large share of this market.
A CPA-prepared profit and loss statement in place of full tax documentation. Another route for business owners whose income is real but awkward to evidence the conventional way.
Qualify on the strength of your assets rather than a monthly paycheck. Useful for retirees and for buyers whose wealth sits in a portfolio rather than in income.
Draw against the equity in a home you already own — for renovations, a second property, or to fund a purchase while you wait to sell. Tap into my equity.
Meet your broker
“I have worked with American Mortgage Solutions multiple times now, and as a repeat customer, I can confidently say they are the best in the business.”
Kerry Rexroad · Google review
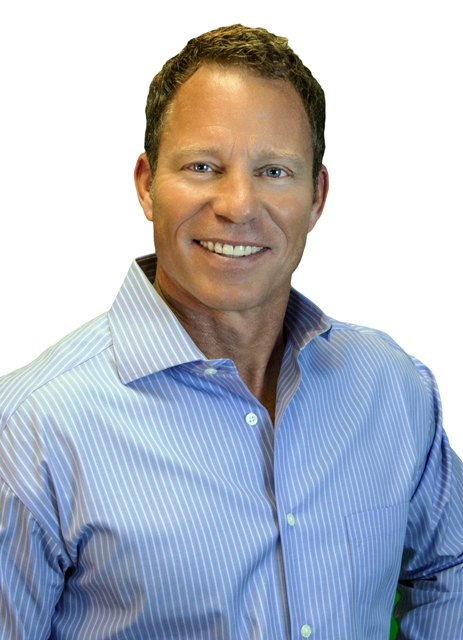
Brady Webb has originated mortgages for more than two decades across Florida and Kentucky, and as President of American Mortgage Solutions he has built the firm around a straightforward premise: a broker’s job is to shop your file, not to sell you a product.
That matters more in Cape Coral than in most markets. Construction-to-permanent lending is not offered by every lender, and the ones who do offer it vary widely on draw process, builder requirements, and how long they will let a build run. Non-warrantable condominium programs, DSCR investor loans and short-term rental financing are similarly uneven across the industry.
A single bank either has the product you need or it does not. Working with many lenders means the answer to an unusual scenario is usually “here are your options” rather than “no.”
Questions
Not harder, but appraised differently. The premium a Gulf-access lot carries is real and the comparable set is narrower, so a weak appraisal is the most common way these deals wobble. Flood and wind insurance also land heavier on the monthly payment, which affects what you qualify for. Both are manageable when they are raised at pre-approval rather than in underwriting.
Usually yes. A construction-to-permanent loan can cover the lot purchase and the build, then convert to your permanent mortgage at completion without a second closing. If you already own the lot outright, its value typically counts toward your equity, which can reduce what you need to bring in cash.
Confirm it with the city before you buy, because it changes both cost and timeline. An unconnected lot needs well and septic, and a lot on a street where utilities are being installed may carry an assessment that transfers with the property. Either can move a build budget by a meaningful amount.
Yes. Conventional investment financing where it fits, and DSCR loans that qualify on the property’s rental income rather than your personal tax returns — which is how most Cape Coral short-term rental purchases get done.
Enough to change your price range. On an inland house it is one line; on a Gulf-access property in a flood zone, flood and wind can push it several times higher. Run the calculator above with a real quote rather than an estimate — it is the figure that moves the answer most here.
Thirty to forty-five days is typical for an existing home. A build runs to its own schedule and converts at completion. The items that most often add time here are insurance binders, seawall or four-point inspections, and well and septic testing.
Waterfront, new construction, first home, investment property or refinance. Tell us what you are working on and we will tell you what is realistic.
Serving Cape Coral, Pine Island, Matlacha, Burnt Store, North Fort Myers and all of Lee County.