dscr loan

DSCR Loan Requirements: How to Qualify for an Investment Property.
-
Brady Webb
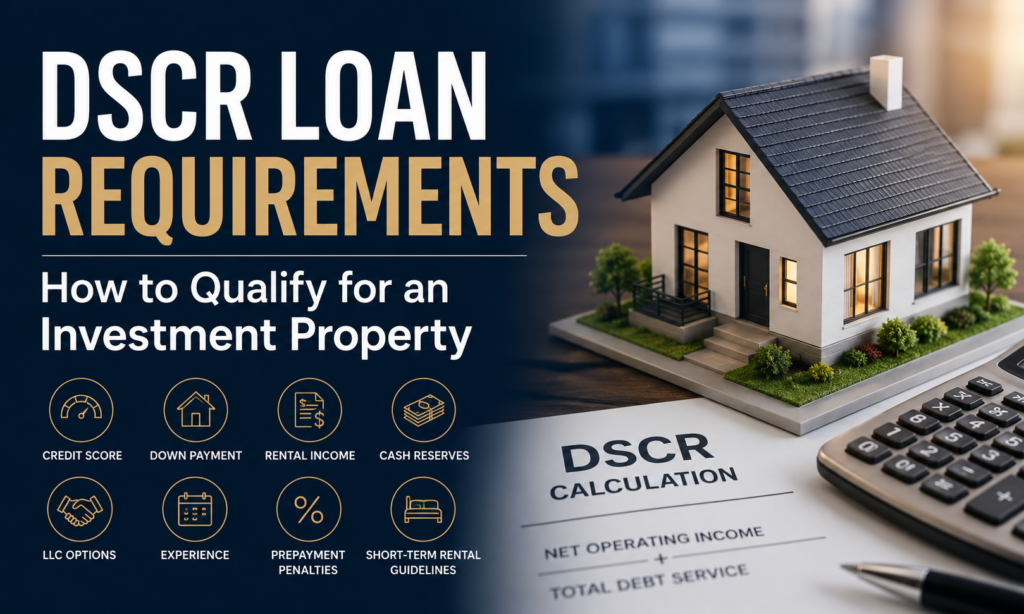
If you're considering a DSCR loan for an investment property, the next question is simple:
What do you need to qualify?
DSCR loan requirements can vary significantly between lenders. Your credit, down payment, rental income, property type, cash reserves, and investment experience can all affect which programs are available.
Here are some of the most important things to know before applying.
Can First-Time Investors Qualify for a DSCR Loan?
Yes. DSCR financing isn't limited to experienced landlords or investors with large real estate portfolios.
Some lenders offer programs for first-time real estate investors, although the requirements may differ from those available to experienced investors.
Depending on the lender, a first-time investor may need stronger credit, additional reserves, or a larger down payment.
The important takeaway: Don't assume you need previous investment-property experience to qualify.
What Credit Score Do You Need for a DSCR Loan?
There isn't one universal minimum credit score for every DSCR loan.
Generally, stronger credit can provide access to more programs and potentially better pricing. Your credit profile can also affect your:
- Down payment requirement
- Interest rate
- Maximum loan-to-value
- Reserve requirements
If your credit isn't perfect, that doesn't necessarily eliminate DSCR financing. It may simply change which lender or program is the best fit.
How Much Down Payment Is Required?
DSCR loans typically require a larger down payment than a primary-residence mortgage.
The exact amount can vary based on the lender, credit score, property type, loan amount, and strength of the overall transaction.
A larger down payment can also help the property qualify because reducing the loan amount generally lowers the monthly mortgage payment.
Before making an offer, we can review different down-payment scenarios to see how they affect both the financing and your potential cash flow.
How Will the Lender Determine Rental Income?
Rental income is one of the most important pieces of a DSCR loan approval.
Depending on the property and program, lenders may consider an existing lease, market rent determined through an appraisal, or other acceptable rental documentation.
One common mistake is assuming the advertised or projected rent on a property listing will automatically be the amount the lender uses.
It may not be.
That's why it's smart to review the property's potential qualifying rent before you're too far into the transaction.
What About Airbnb and Short-Term Rentals?
Certain DSCR lenders offer financing for Airbnb, VRBO, vacation rentals, and other short-term rental properties, but the guidelines can be different from those for traditional long-term rentals.
How the lender calculates short-term rental income can be especially important.
If you're considering a short-term rental, we want to identify lenders that actually work with that type of property rather than trying to fit the deal into a program that wasn't designed for it.
Can You Purchase a DSCR Property in an LLC?
Many DSCR programs allow eligible investment properties to be purchased or held in an LLC.
The lender may require additional entity documentation, and the individual borrower may still be required to personally guarantee the loan.
Because the way you hold title can have legal and tax consequences, you should discuss the appropriate ownership structure with your attorney or tax professional.
Are Cash Reserves Required?
Depending on the lender and loan program, you may be required to have a certain amount of money remaining after closing.
These cash reserve requirements can vary based on factors such as your credit profile, loan amount, property, and overall transaction.
This is something we want to know upfront so there aren't any surprises shortly before closing.
Watch for Prepayment Penalties
This is one area investors shouldn't overlook.
Some DSCR loans may include a prepayment penalty if the loan is paid off within a specified period. That can matter if your strategy is to sell the property or refinance relatively quickly.
When comparing DSCR loans, don't look only at the interest rate.
You should understand the rate, fees, down payment, reserves, and prepayment terms before choosing a program.
Why Shopping DSCR Lenders Matters
Perhaps the most important thing to understand about DSCR loan requirements is that they aren't identical from lender to lender.
One lender may be better for a first-time investor. Another may be more competitive for an Airbnb or short-term rental. Another may offer more flexibility based on credit, reserves, or property type.
That's one advantage of working with American Mortgage Solutions. As a mortgage broker, we can compare programs from multiple wholesale lenders instead of being limited to one bank's guidelines.
Ready to See What You Qualify For?
Whether you're purchasing your first investment property or adding another rental to your portfolio, let's look at the property and your financing options before you make your next move.
📞 Contact Brady Webb
🌴 American Mortgage Solutions
📍 Cape Coral, FL: (239) 766-8344
📍 Louisville, KY: (502) 327-9770

Do you know how much home you can afford?
Most people don’t... Find out in 10 minutes.
Your Mortgage Broker in Cape Coral FL & Louisville KY. We are licensed in Florida, Kentucky, and Indiana.
- Services
- Blog
- Locations
- Contact


Copyright © 2026 | American Mortgage Solutions | NMLS: 1364/MB73346
Licensed in: FL, KY, IN
FL-MBR1574, KY-MB73346
Copyright © 2026 | American Mortgage Solutions | NMLS: 1364/MB73346
Licensed in: FL, KY, IN
FL-MBR1574, KY-MB73346
American Mortgage Solutions follows all Equal Housing laws. As prohibited by federal law, we do not engage in business practices that discriminate on the basis of race, color, religion, national origin, sex, marital status, age, because all or part of your income may be derived from any public assistance program, or because you have, in good faith, exercised any right under the Consumer Credit Protection Act. Disclaimer: Programs subject to change without notice. All borrowers must qualify per program guidelines.
These materials are not from HUD, FHA, the USDA, or the VA. These materials were not approved by any government agency. They are independent of any government agency. We are not in any way affiliated with any organization listed or referenced within this website, including HUD/FHA/USDA/VA. The inclusion of various education, information, web links, or materials are not an endorsement of the Sender or any of its employees or business partners. For information directly from HUD/FHA, visit https://www.hud.gov/guidance For information directly from the VA, visit http://www.benefits.va.gov/HOMELOANS/ For information directly from the USDA, visit http://www.usda.gov/wps/portal/usda/usdahome?navid=GRANTS_LOANS