Financing a home here means dealing with things buyers in other markets never think about: flood zones, wind mitigation, roof age, insurance binders that have to be in place before your loan can close. We would rather talk to you about those at pre-approval than have them surprise you three days out.
“I have worked with American Mortgage Solutions multiple times now, and as a repeat customer, I can confidently say they are the best in the business.”
Kerry Rexroad · Google review
Fort Myers numbers at a glance
The numbers that decide what you can buy
Lee County, 2026
Conventional / conforming, 1-unit$832,750
Conforming, 2-unit$1,066,260
Conforming, 3-unit$1,288,800
Conforming, 4-unit$1,601,760
FHA, 1-unit$541,287
VANone, full entitlement
USDAEligible areas only — address-specific
Effective property tax rate~0.79%
Typical closing30–45 days
What this table does not tell you is what the property costs to hold — and in Lee County that is usually the binding constraint, not any borrowing ceiling. Insurance and community assessments enter the same debt-to-income calculation as your loan payment, so they reduce what you can borrow before a limit ever becomes relevant. The tool alongside runs that arithmetic.
Loan limits are the 2026 FHFA and HUD figures for Lee County, Florida. The tax rate is a county-level effective rate; your own assessment will be set by the Lee County Property Appraiser.
Cost of carry
What it costs to hold a Fort Myers home
National affordability calculators consistently overestimate here, because they assume insurance and association dues that look nothing like Lee County’s. Swap in the same numbers that will end up on your file.
$
Assumptions — edit any of these
%
%
$
$
%
Estimated monthly cost to hold
$3,648/mo
Principal & interest$2,560/mo
Property tax$405/mo
Insurance$433/mo
Dues & assessments$250/mo
30% of this payment is not loan repayment.$1,088 a month goes to tax, insurance and dues, but lenders count all of it against your debt-to-income ratio — which is why it changes what you can borrow, not just what you pay.
This is an illustration, not an offer. Figures are built from the assumptions above; your own rate, taxes, insurance premium and association dues will differ. Mortgage insurance, flood insurance and closing costs are not included.
Lee County tax bills are not fixed at the county rate. The millage that applies to a given address depends on the municipality and any special districts it sits in, and a purchase resets the assessed value to the sale price. The estimate above is deliberately set a little above the headline effective rate for that reason, since a recent purchase is usually what we are pricing. Brady can pull the actual millage for the address you are considering before you make an offer.
By neighborhood
Different parts of Lee County, different considerations
McGregor Boulevard & historic downtown
Older, established housing stock. Expect a four-point inspection on almost anything past a certain age, and be ready for roof age to become a live issue with your insurance carrier before it ever becomes one with your lender.
Fort Myers Beach & Sanibel
Coastal, high-value, almost always in a flood zone. Elevation certificates matter here, many properties are condominium, and where they are the association’s finances and insurance get underwritten alongside your loan.
Gateway & the Daniels corridor
Newer construction and planned communities. Lower roof risk, but CDD assessments are common here, and they count in your debt-to-income calculation and therefore reduce how much you qualify for.
Whiskey Creek & Iona
Mid-century stock, 1970s to 1990s homes at more accessible price points. Strong first-time-buyer territory, with the same roof and plumbing questions that come with anything of that age.
North Fort Myers & Buckingham
More acreage, larger parcels, and some addresses that qualify for USDA zero-down financing. Well and septic systems need their own inspections, and those take time you should build into the contract.
Lehigh Acres
Large lot inventory and active new construction. Utility connection status matters: some lots have central water and sewer and some are still well and septic — confirm which one you are buying before you write the offer.
The extra hurdles
Insurance, flood zones, and what they do to your loan
Your lender does not just approve you. It approves the property — and in Lee County that approval runs through insurance.
Insurance has to be bound before you close
You can be fully approved and still miss your closing date, because a bound policy is a closing condition. The premium is also part of your monthly payment, so an unexpectedly high quote directly reduces how much you qualify for — sometimes enough to change the price range you are shopping in.
Flood insurance is required in some zones, not others
If the property sits in a FEMA Special Flood Hazard Area and you are financing with a federally related mortgage, coverage is mandatory. An elevation certificate can change the premium significantly — ask whether one exists before you assume the quoted figure is final.
Roof age and the four-point inspection
Carriers care a great deal about roof age, and on older homes many require a four-point inspection covering roof, electrical, plumbing and HVAC. A carrier declining coverage over an aging roof can stop a loan that had no underwriting problem whatsoever.
Permit history on repair work
A house that took storm damage, was repaired without permits, and shows up that way in the county record is harder to finance than one with a clean file. Title and survey turn this up, and FHA and VA appraisers in particular will call out unpermitted repairs.
None of this should be discouraging — thousands of Fort Myers homes finance and close smoothly every year. But these are solvable problems in pre-approval and expensive problems in escrow. Raising them early is a large part of what you are hiring a local broker to do.
Questions
Fort Myers mortgage questions
It depends on the specific property. If it sits in a FEMA Special Flood Hazard Area and you are financing with a federally related mortgage, yes. Plenty of Lee County addresses are not in one. We run the flood zone determination early so your budget is accurate from the start rather than after you are under contract.
Your debt-to-income ratio, and in Southwest Florida that calculation is unusually sensitive to what the property costs to hold. Taxes, insurance, flood and any HOA or CDD assessment all sit on the same side of the ledger as the loan payment. Two identical borrowers can qualify for very different amounts on two houses at the same price.
Often, yes — but the building gets underwritten as well as you do. Lenders look at the association’s reserves, its insurance, the owner-occupancy ratio and any pending special assessments or structural work. We check whether a building is approved or warrantable before you spend money on inspections.
Run the calculator above with real Lee County insurance and assessment numbers and you will get much closer than a national affordability tool will. Then let us verify the figures against a specific address — the tax and insurance side moves the answer far more here than most buyers expect.
Yes. Conventional investment financing, and DSCR loans that qualify on the property’s rental income rather than your personal tax returns — which is how most of the short-term rental purchases in this market get done. More on DSCR loans.
Thirty to forty-five days is typical for a purchase. The items that most often add time here are insurance binders, a four-point or wind mitigation inspection on an older home, and well and septic testing on rural parcels. All three can be started early, and we do.
Options
Financing options available in Lee County
Program
Best for
Minimum down
2026 Lee County cap
Conventional
Solid credit, broader flexibility
3–5%
$832,750
FHA
Lower credit scores, smaller down payment
3.5%
$541,287
VA
Eligible veterans and service members
0%
No limit, full entitlement
USDA
Eligible rural addresses, income limits apply
0%
Area-specific
Above conforming
Purchases above the standard county limit
Varies by lender
Above $832,750
DSCR / investor
Rentals, qualifying on rent not personal income
Typically 20–25%
Lender-specific
Renovation
Homes needing repair or updating
Varies
Program-specific
Refinance
Lower payment, shorter term, cash out, drop MI
—
Program-specific
B.W.
RolePresident, American Mortgage Solutions
Experience20+ years originating
LicensedFlorida, Kentucky & Indiana
NMLS#36093
Specialises inNew construction, condo review, first purchase
Meet your broker
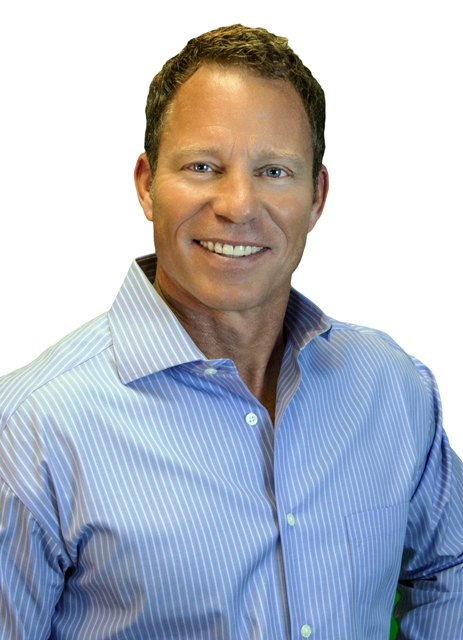
Brady Webb
Brady Webb is the President of American Mortgage Solutions and has spent more than twenty years originating loans across Florida and Kentucky.
He has been financing Southwest Florida property through a genuinely eventful stretch for this market — the run-up in values, the hard reset in the insurance market, the post-Ian rebuilding. That history is worth something specific in Fort Myers: the insurance and property-condition problems described above are not news to him.
His approach is to tell clients what is actually going to happen, including when the answer is that a particular property or program will not work. Most people find that more useful than optimism.
Get a straight answer on Fort Myers financing
Tell us what you are trying to buy. We will tell you what is realistic, including the insurance and assessment numbers most calculators leave out.
Serving Fort Myers, Fort Myers Beach, North Fort Myers, Sanibel, Estero, Lehigh Acres, Iona, Buckingham and all of Lee County.