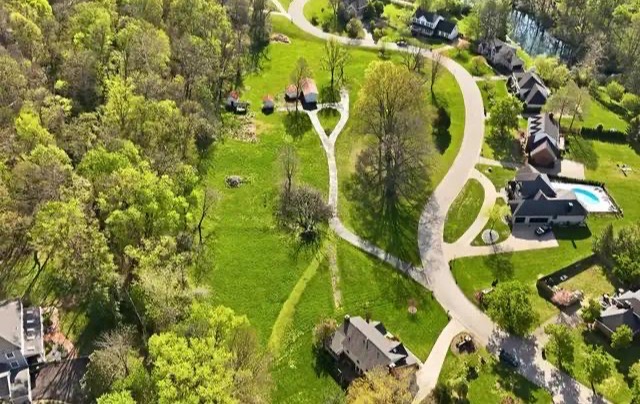
An Oldham County neighbourhood at sunset

Oldham County, KY

Six communities, one county, and the highest property tax bill in Kentucky.

Home values sit well above the state average, the school district is consistently among Kentucky’s highest ranked, and buyers relocating from out of state often find both facts quickly — usually with an affordability number that does not account for the county’s tax rate. It is also six genuinely different places with six different sets of financing considerations.

The Oldham County courthouse in La GrangeLa Grange
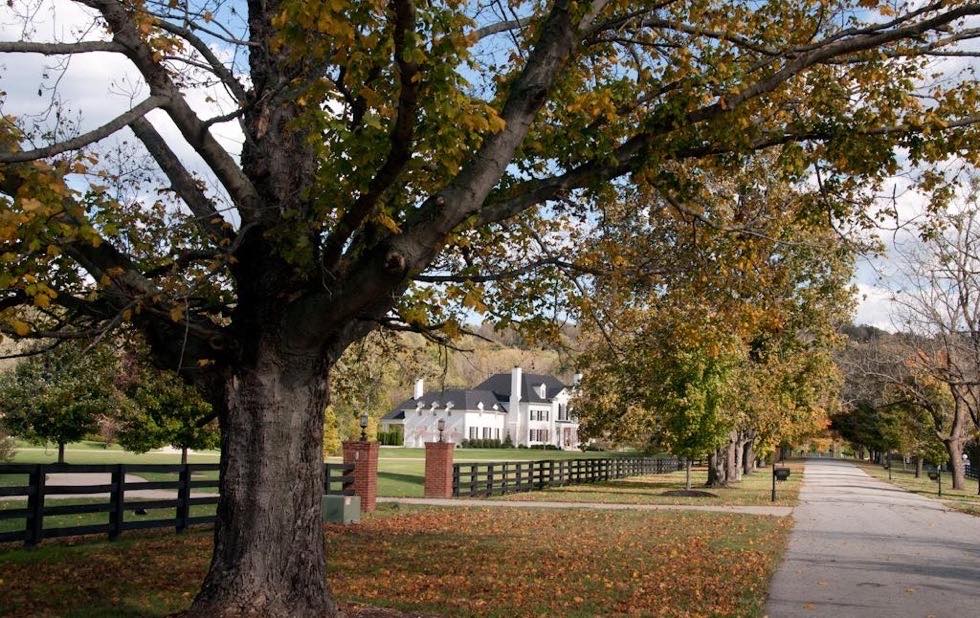
A white home behind plank fencing in Oldham CountyCrestwood
Large homes on wooded lots in Oldham CountyProspect
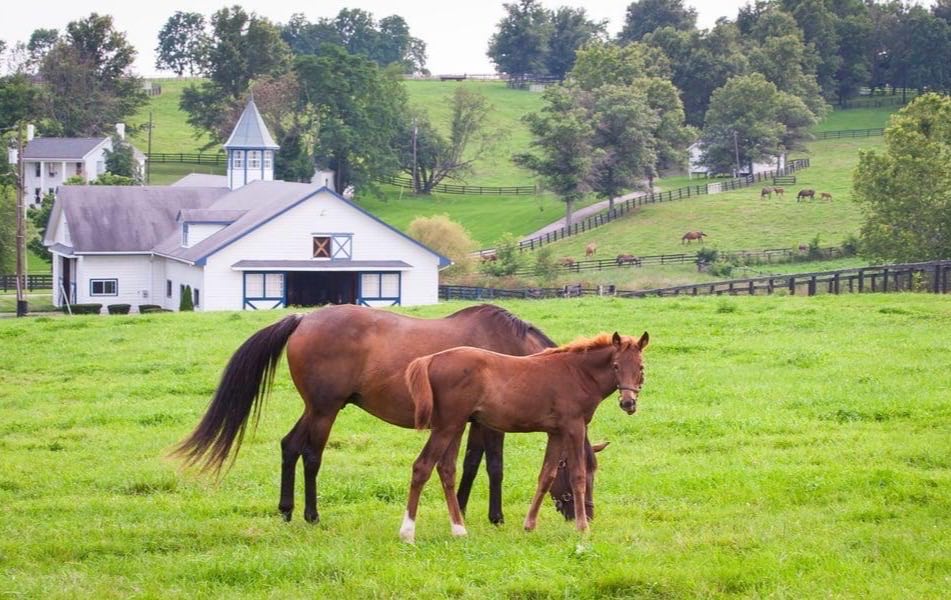
A mare and foal at a horse barn in Oldham CountyGoshen
Pewee Valley and Orchard Grass HillsPewee Valley & Orchard Grass Hills
Buckner and BallardsvilleBuckner & Ballardsville

The changing communities

What changes from town to town

La Grange

County seat · historic centre, older stock, new build on the edges
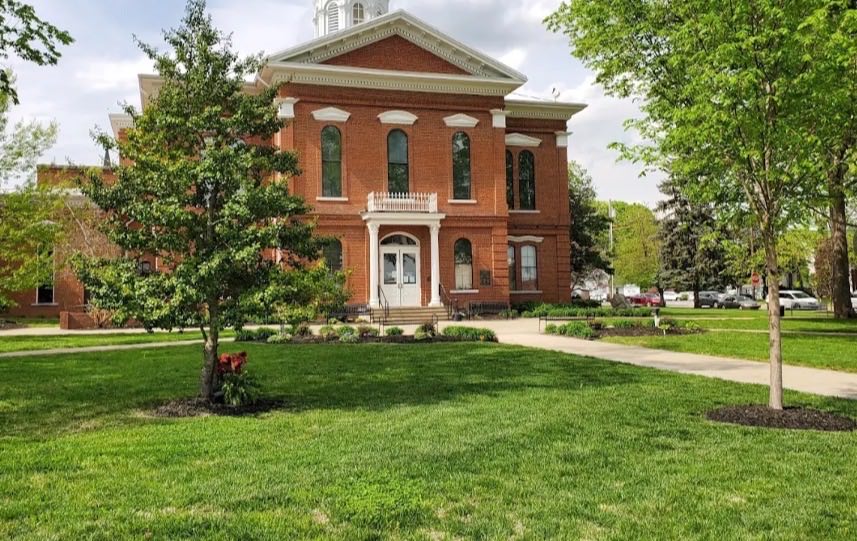
La Grange, Oldham County

Rural in feel and small in scale, with the county’s oldest housing stock around a walkable historic centre, and newer subdivisions filling in at the edges.

What it means for your loan: La Grange is where the full programme mix applies. Conventional, FHA and VA all work comfortably, and addresses toward the county’s outer edges may qualify for USDA zero-down financing. The older stock near the centre is also where a renovation loan — FHA 203(k) or Fannie Mae HomeStyle — is often a more sensible route than a standard purchase.

Can I use FHA in La Grange?

Yes. The FHA limit in Oldham County is $541,287, which covers the great majority of La Grange housing stock. Remember that FHA applies stricter minimum property standards, which matters on the older houses near the centre.
Crestwood

New construction · family demand, school-driven

A white home behind plank fencing in Oldham County

The county’s most active new-construction market, and the place most out-of-state buyers end up looking first.

What it means for your loan: mostly builder dynamics. Builders offer incentives tied to using their preferred lender, and those are worth pricing against the market rather than accepting at face value. Read the wording carefully: in most cases the incentive survives you shopping the loan.

Should I use the builder’s lender in Crestwood?

Get their offer, then let us price it beside it. Sometimes the incentive is genuinely good and sometimes it is a credit that costs more in rate than it returns at closing. You usually do not have to give up the incentive to compare — but read the contract, because a minority of builders do tie them together.

Prospect

Upscale · and split across a county line

Large homes on wooded lots in Oldham County

Higher price points, larger lots, and the one place in the county where the address itself is a financing question.

What it means for your loan: above the conforming ceiling a loan is priced file by file rather than to a published sheet, and reserve requirements and rate differ meaningfully between lenders. Several Prospect developments also carry HOA dues that count in your debt-to-income calculation.

Important local detail

The city of Prospect straddles the Jefferson–Oldham county line. Two houses on the same street can sit in different counties, which changes the property tax rate, the school assignment and which county’s loan limits apply. It is a genuine and recurring source of buyer error here.

Is my Prospect address in Oldham or Jefferson County?

It depends on the specific parcel, and it is worth confirming before you make an offer. The county decides your property tax rate, your school assignment and which county’s loan limits apply — and because taxes sit inside your monthly payment, they change what you qualify for. We check it as a matter of course.

Goshen

River frontage · acreage and estate properties

A mare and foal at a horse barn in Oldham County

Ohio River frontage, larger parcels, and the kind of property where the appraisal becomes the whole conversation.

What it means for your loan: land changes the appraisal. Excess acreage often contributes far less than it cost, because residential appraisals value a house and a typical home site; outbuildings usually contribute close to nothing. Past a certain point a property is agricultural rather than residential, at which point conventional programmes stop applying and Farm Credit financing is the right route. Well, septic and legal road access each add an inspection.

How does acreage affect financing in Goshen?

Mostly through the gap between price and appraised value. Send us the listing before you write an offer and we will tell you how a residential appraisal is likely to treat the land and the outbuildings, and whether the property sits near the agricultural line.

Pewee Valley & Orchard Grass Hills

Small, established, and thinly traded

Pewee Valley and Orchard Grass Hills, Oldham County

Two of the smallest communities in the county, and the ones where comparable sales are hardest to come by.

What it means for your loan: appraisal risk. Few transactions means an appraiser is working from thin data, and a value that lands under the contract price comes out of your pocket. It is the single thing most worth anticipating here, and it is anticipatable.

What if the appraisal comes in low in Pewee Valley?

You have options, and they are better ones if you saw it coming. You can bring the difference in cash, renegotiate, or in some cases request a reconsideration of value with better comparable sales. We flag thin-comp risk before you write rather than after the report lands.

Buckner & Ballardsville

The rural edge — where zero-down may apply

Buckner and Ballardsville, Oldham County

The county’s rural edge, and the part of Oldham where the most useful programme is the one people assume does not apply to them.

What it means for your loan: USDA eligibility is drawn on population thresholds rather than on how remote somewhere feels, and a good deal of this end of the county qualifies. Zero down, income-limited by household size, and address-specific. Beyond that, well and septic testing is common out here and it has its own schedule.

Does USDA work in Buckner?

Often, yes — and it is worth checking a specific address rather than assuming. The eligibility map follows population rather than distance, so places that feel thoroughly suburban sometimes qualify and places that feel rural sometimes do not.

Cost of carry

What an Oldham County property costs to hold

This is the section that catches people relocating in. Oldham carries the heaviest property tax burden in the state, and a national affordability calculator will not know that.

$

Assumptions — edit any of these

%
%
$
$
%

Estimated monthly cost to hold

$3,744/mo

Principal & interest$2,987/mo
Property tax$473/mo
Insurance$200/mo
Dues & assessments$85/mo

20% of this payment is not loan repayment. $758 a month goes to taxes, insurance and dues. Against Shelby or Jefferson County that difference is real money, and it is the single number most worth establishing before you settle on a price range here.

This is an illustration, not an offer. Your own rate, taxes, insurance premium and any HOA dues will differ, and mortgage insurance is not included. A Prospect address on the Jefferson County side of the line carries a different tax rate again.

Above the limit

What changes on a higher-value purchase

A good share of Oldham purchases sit above the conforming ceiling, where the rules stop being uniform.

Appraisals carry more risk, not less

Counties like this one have comparatively few high-value transactions, so an appraiser working at the top of the market has a thinner set of comparable sales to draw on. Estate properties and river frontage compound it further.

Reserves become a requirement

Above the conforming limit lenders want to see months of payments held in reserve after closing, and how many months differs between them. It is a genuine qualifying criterion rather than a formality, and it catches buyers who put every available dollar into the down payment.

Documentation goes deeper

Expect more scrutiny of income, assets and the source of your down payment, particularly if any part of it is self-employment income, an equity position from a departing market, or a gift.

How the financing is structured is worth comparing

Above the limit, pricing is set file by file. Rate, reserve requirements and down payment expectations all differ meaningfully between lenders, which means comparing several is worth real money rather than being a box to tick.

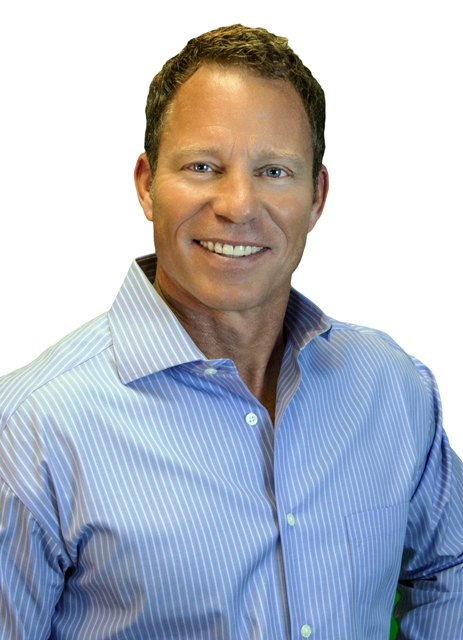
Brady Webb, President of American Mortgage Solutions
RolePresident, American Mortgage Solutions
Experience20+ years originating
LicensedFlorida, Kentucky & Indiana
NMLS#36093
Specialises inRelocation, higher-value purchase, new build

Meet your broker

Brady Webb

Brady Webb is the President of American Mortgage Solutions and has been originating loans across Kentucky for more than twenty years. Oldham County sits directly in the territory the firm has worked longest.

It is a county that rewards specificity. A La Grange renovation loan, a Crestwood builder contract, a Goshen property with acreage and a Prospect address on the wrong side of a county line are four unrelated problems, and a lender with one product will treat them as though they were the same one.

Working with many lenders means an awkward file usually has an answer somewhere. Finding it is the entire job.

New to the county

Relocating to Oldham County

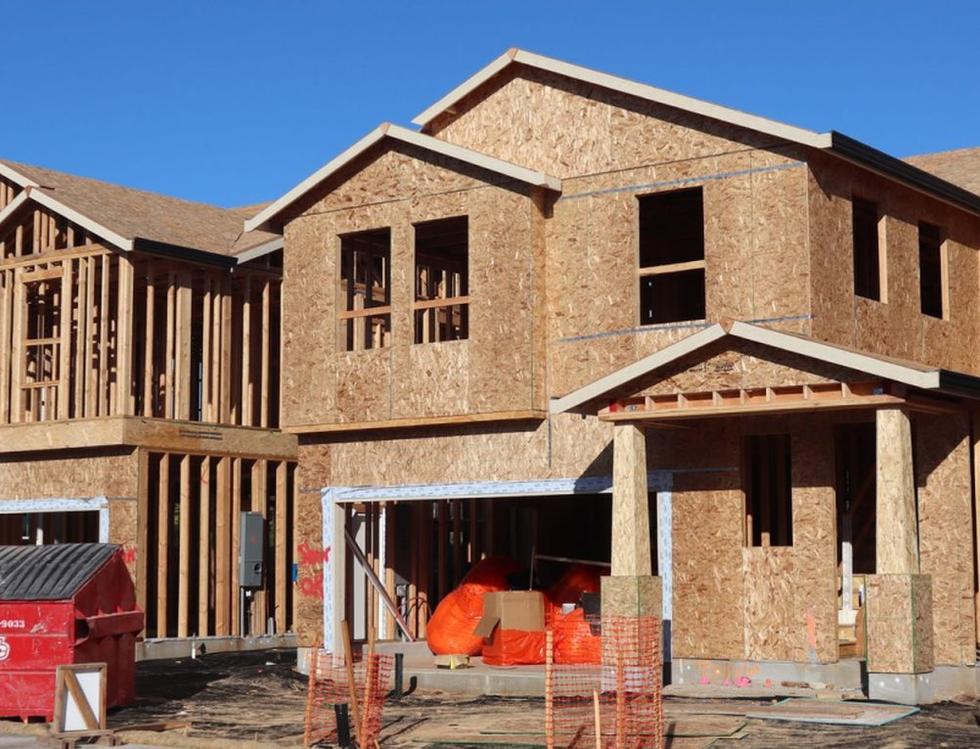
A newly built Oldham County home

The school district is what brings most people here, and it is usually what they have already researched. The financing is the part that gets researched last.

  • Run the tax rate first. If your budget came from a national calculator, it is very likely too generous for this county. Establish the real monthly figure before you fall in love with a price range.
  • Two closings, one plan. Buying here before you have sold elsewhere is routine, but the order of operations matters and the equity timing needs mapping out in advance.
  • Confirm the county on a Prospect address. If you are looking at that end of the market, the county line changes your taxes, your schools and your qualifying amount.
  • Get pre-approved before you travel. Buyers relocating often see everything in one weekend and need to write quickly. A documented pre-approval is what makes that possible.

Get a real number for Oldham County

Send us an address or a community and we will come back with the actual carrying cost, including the tax line that national calculators get wrong here — and, on a Prospect address, which county it is in.

Serving La Grange, Crestwood, Prospect, Goshen, Pewee Valley, Orchard Grass Hills, Buckner, Ballardsville and all of Oldham County.

American Mortgage Solutions follows all Equal Housing laws. As prohibited by federal law, we do not engage in business practices that discriminate on the basis of race, color, religion, national origin, sex, marital status, age, because all or part of your income may be derived from any public assistance program, or because you have, in good faith, exercised any right under the Consumer Credit Protection Act. Disclaimer: Programs subject to change without notice. All borrowers must qualify per program guidelines.

These materials are not from HUD, FHA, the USDA, or the VA. These materials were not approved by any government agency. They are independent of any government agency. We are not in any way affiliated with any organization listed or referenced within this website, including HUD/FHA/USDA/VA. The inclusion of various education, information, web links, or materials are not an endorsement of the Sender or any of its employees or business partners. For information directly from HUD/FHA, visit https://www.hud.gov/guidance For information directly from the VA, visit http://www.benefits.va.gov/HOMELOANS/ For information directly from the USDA, visit http://www.usda.gov/wps/portal/usda/usdahome?navid=GRANTS_LOANS