Conventional
Competitive rates and flexible terms for buyers with solid credit, plus the option to drop mortgage insurance once you reach 20% equity.
Naples · Collier County, FL
Beachfront condominiums, bundled golf communities, second homes, seasonal residences, waterfront properties with no true comparable sale. Naples financing gets complicated in specific, predictable ways — and a lender with one product line runs out of answers fast.

Cost of ownership
The numbers that actually decide what you can afford here.
The mortgage is only part of the monthly burden, and in Collier County it is often not the part that decides what you can afford. Adjust the assumptions and watch which line item moves your payment most.
Purchase price
Assumptions — edit any of these
Estimated monthly cost to hold
$6,395/mo
31% of this payment is not loan repayment. $1,971 a month goes to taxes, insurance and dues, but lenders count all of it against your debt-to-income ratio, which is exactly why it changes what you can borrow — not just what you pay.
This is an illustration, not an offer. Figures are built from the assumptions above; your own rate, taxes, insurance premium and association dues will differ. Mortgage insurance, flood insurance and closing costs are not included.
Collier County’s effective property tax rate is among the lowest in Florida, which is the one line item that works in a Naples buyer’s favour. Insurance and association dues usually run the other way, and on a bundled golf or beachfront condominium the dues alone can outweigh the tax bill several times over. Brady can pull the real figures for a specific address before you make an offer.
Why a broker
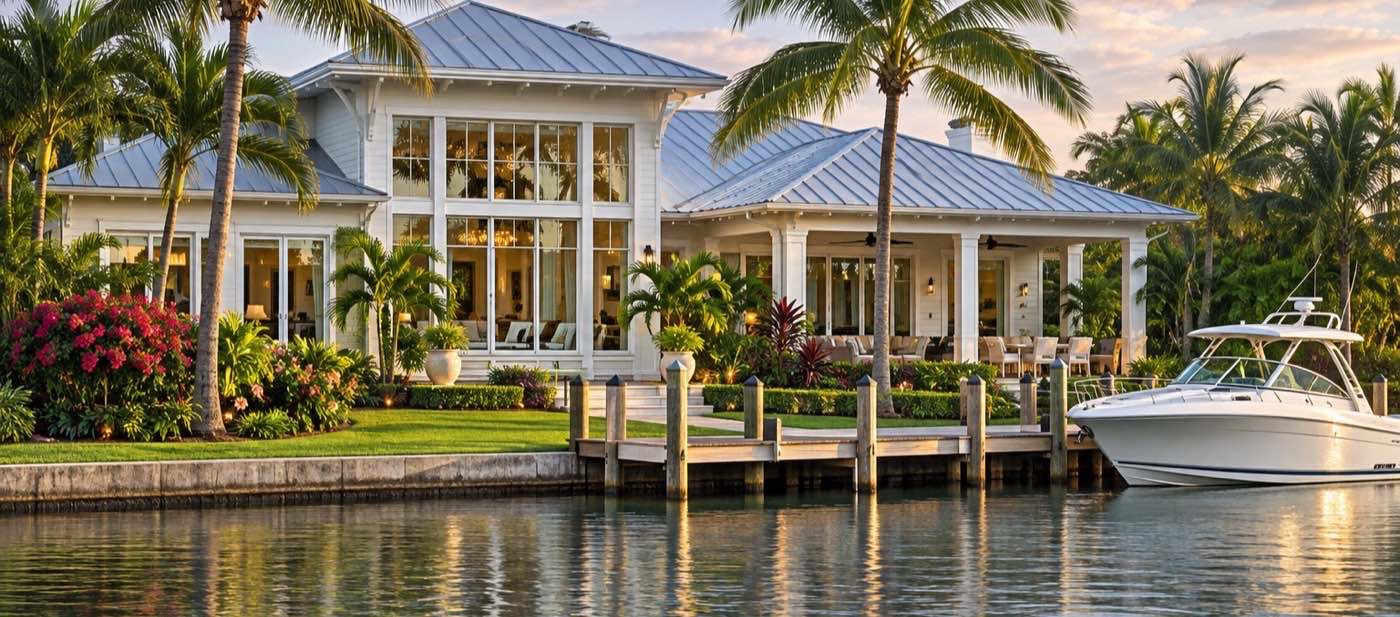
Naples is one of Florida’s most competitive housing markets, and it is unusually varied. Park Shore and Vanderbilt Beach condominiums, golf communities like Grey Oaks and Fiddler’s Creek, growing family neighborhoods east of Collier Boulevard, seasonal residences on Marco Island — each carries its own financing considerations.
Working with an experienced Naples mortgage broker means having someone who already knows where these deals get difficult: condominium project approvals, seasonal and self-employment income documentation, second-home occupancy rules, appraisals on one-of-a-kind waterfront property.
Instead of fitting you to a single loan, we understand your financial picture first, then recommend options. And we stay available through the whole loan, so you are never guessing what happens next.
Meet your broker
For more than two decades Brady Webb has helped individuals and families finance homes across Florida and Kentucky. As President of American Mortgage Solutions, he has built the firm around responsiveness and finding financing that fits the client’s actual situation.
His work spans first-time buyers through luxury purchases, investment property, vacation homes, and the complex scenarios that come up constantly in a market like Naples — where a buyer’s income is often self-employment, retirement distributions or business income rather than a straightforward W-2.
Clients recommend Brady because they get a direct answer quickly, including when the answer is that a particular property or program will not work.
Programs
No two borrowers have the same goals, so we work across a wide range of programs.
Competitive rates and flexible terms for buyers with solid credit, plus the option to drop mortgage insurance once you reach 20% equity.
Lower down payment and more forgiving credit guidelines. Useful more often than Naples buyers expect, though the county loan limit caps what it can reach.
Eligible veterans and service members can buy with zero down, no monthly mortgage insurance and competitive rates, with no loan ceiling on full entitlement.
Above the conforming limit a loan is priced file by file rather than to a published grid. Reserves, down payment and rate genuinely differ by lender, so comparison pays.
Occupancy rules on a Naples second home are stricter than on a primary residence, and rental history changes the category. We confirm which one you are actually buying before underwriting decides for you.
Conventional investment financing plus DSCR programs that qualify on the property’s rental income instead of your personal income — useful when your return is the stronger case. More on DSCR.
Plenty of financeable Naples buildings fail the standard warrantability tests — litigation, investor concentration, a single owner holding too many units. Some lenders write these deals. Most will not.
Lower your payment, shorten your term, or take out equity. We show you the break-even honestly, including when the answer is to stay put.
The process
Five stages, and where each one usually stalls.
Review income, assets, credit and goals, and establish what you can comfortably afford — using real local insurance and association figures, not a national calculator’s estimate.
A documented pre-approval carries real weight with sellers. In Naples, where inventory moves fast, that is often what separates the winning offer from the rest.
Once you are under contract we collect the remaining documents: title, appraisal, insurance binder, condominium questionnaire where the building requires one.
The underwriter reviews the whole file. If anything comes back as a condition, we handle it rather than hand it to you.
Final approval, closing disclosure, signatures, keys. Most Naples purchases close in 30 to 45 days.
Broker vs bank
A bank can only offer what is in its own catalogue. If your file falls outside it, the answer is no — with nowhere else to go.
Because we work with multiple lending partners, we shop your file rather than fit it to one institution’s box. In Naples that difference shows up in four recurring situations:
Client experience
5.0 from 100 reviews on Google. A few of them, in their own words.
★★★★★
“Brady and his team were fantastic! From dealing with Brady about my requirements and being nervous to know if I had all the requirements, Brady kept me at ease. He explained everything calmly and literally walked me each step of the way.”
★★★★★
“I have worked with American Mortgage Solutions multiple times now, and as a repeat customer, I can confidently say they are the best in the business.”
★★★★★
“He was super friendly and helpful. He communicates very well and definitely provides a high level of service. He is very good at explaining things in a way I understand.”
Questions
It depends on program and property type. Some conventional programs allow as little as 3% down for qualified first-time buyers, FHA is 3.5% with qualifying credit, and eligible veterans may put nothing down at all. Second homes and investment properties require more. We will get you specific numbers at pre-approval.
Yes, and it is one of the most common things we do here. Second-home financing carries its own occupancy rules and usually a larger down payment than a primary residence. If you intend to rent it out at all, say so early — that can move the file into investment territory, which is a different program and a different rate.
We start with your financial picture — how your income is documented, what reserves you hold, the property type and your timeline — and then match it against lenders whose guidelines actually fit. A file that is awkward at one lender is routine at another; knowing which is which is most of the job.
That is a lender decision about the building, not about you, and lenders disagree constantly. Litigation, investor concentration, reserve levels or a single owner holding too many units can all trigger a decline. We check the building’s status before you spend money on inspections, and we have non-warrantable options when a project genuinely does not qualify.
Thirty to forty-five days is typical from contract to closing. Condominium questionnaires, insurance binders and appraisals on unusual waterfront property are the three things that most often add time here, and all three can be started early.
Yes — to lower a payment, shorten a term, take out equity or drop mortgage insurance. We will show you the break-even honestly, including when the honest answer is that refinancing today does not pay for itself.
Tell us what you are trying to buy and we will tell you what is realistic — including the insurance and assessment figures most calculators leave out. No cost, no obligation.
Serving Naples, Marco Island, Bonita Springs, Immokalee, the Estates and all of Collier County.