
Lexington · Fayette County, KY

Lexington has a financing wrinkle most cities don’t.

Fayette County’s Urban Service Boundary caps where development can happen, which pushes buyers either into competitive city inventory or out onto acreage in the surrounding Bluegrass. Those are two different loans.

We handle both. Tell us what you have already looked at and we will tell you how it finances.

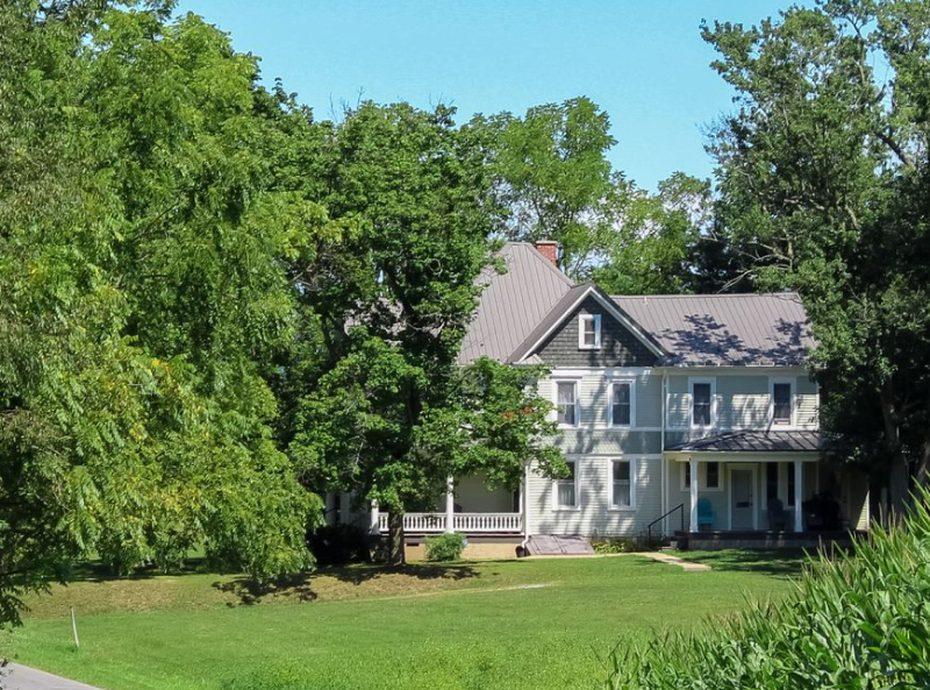
A home on the edge of Lexington

5-Star Service, Proven Results

Five-star rated on Google, Facebook, Zillow and realtor.com; BBB Accredited Business A+

The acreage question

What changes the moment land is involved.

Buying acreage, a farmette, or land

Fayette County’s Urban Service Boundary is the reason. Development inside the county is deliberately constrained, so buyers who want space go looking outside it — and a house on ten acres in Bourbon or Clark County does not finance the way a house on Chevy Chase does.

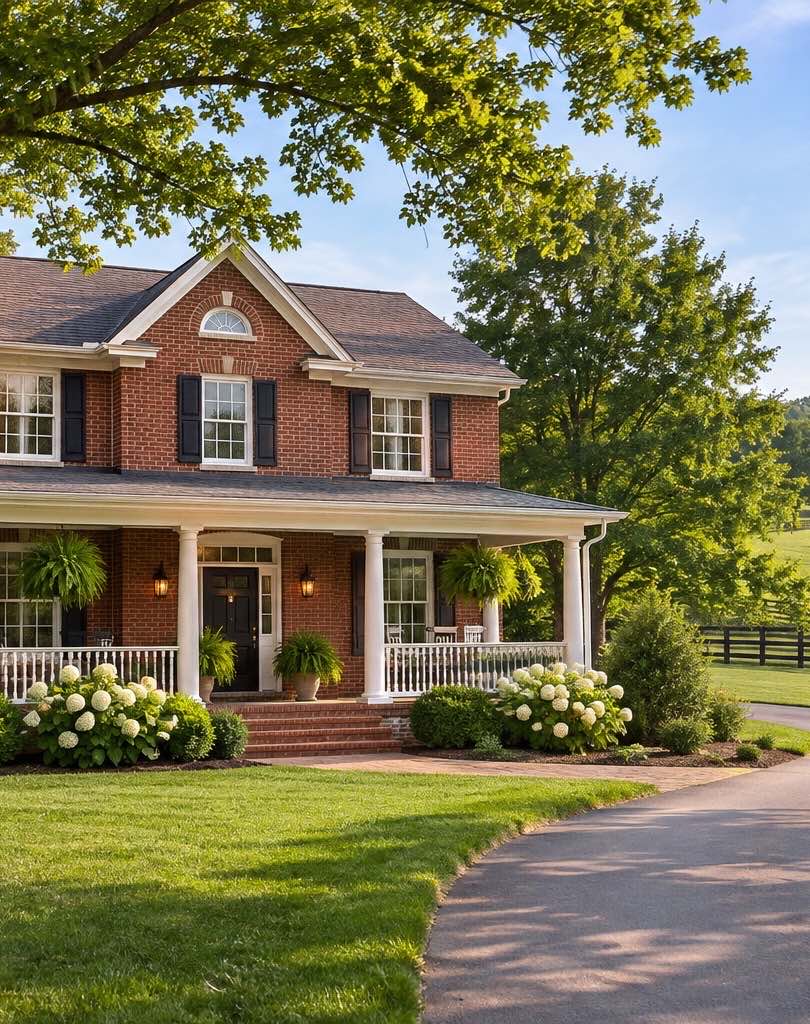
A brick home behind black plank fencing on Bluegrass pasture

What changes when land is involved

Excess acreage may not add appraised value

A residential appraisal values a house and a typical home site. Land beyond that frequently contributes far less to the appraised value than it cost to buy, because the comparable sales an appraiser is allowed to use do not support it. If the appraisal lands under the contract price, that gap comes out of your pocket.

Outbuildings usually contribute little

A barn, a run-in shed or a workshop may be exactly why you are buying the property, and a residential appraisal will still give them close to nothing. Budget accordingly rather than assuming the value carries.

Residential with acreage versus agricultural

There is a line between a house with land and a working agricultural property, and crossing it changes the product. Past a certain point conventional financing stops being available and the answer becomes a portfolio or Farm Credit lender instead. Knowing which side of the line a property sits on is the first question, not the last.

Well, septic, road access

Off municipal services, the property needs its own water, its own waste system and legal access. Each carries an inspection, each takes time, and a shared or unrecorded driveway easement is a genuine underwriting problem rather than a formality.

Raw land is a different product entirely

Buying land now and building later is not a purchase mortgage. It is a land loan: shorter term, larger down payment, fewer lenders offering it, and it should be arranged before you go under contract rather than after.

Cost of carry

What a Fayette County property costs to hold

Kentucky carries cheaply next to the coastal markets: no windstorm exposure, modest insurance and predictable taxes. This is the figure to plan around.

$

Assumptions — edit any of these

%
%
$
$
%

Estimated monthly cost to hold

$2,385/mo

Principal & interest$1,963/mo
Property tax$247/mo
Insurance$175/mo
Dues & assessments$0/mo

18% of this payment is not loan repayment. $422 a month goes to taxes and insurance. On acreage, add well and septic maintenance — neither is escrowed, and neither shows up in a calculator like this one.

This is an illustration, not an offer. Your own rate, taxes and insurance premium will differ, and mortgage insurance is not included. A property on acreage typically carries a higher insurance premium than the in-town default shown here.

Loan programs

How buyers here typically finance

01 · Most common

Conventional
Buyers meeting with their broker

The default for most Lexington buyers. Three to five percent down for qualified first-time buyers, five percent otherwise, and mortgage insurance that comes off once you reach sufficient equity — which is the structural advantage over FHA.

It is also the most flexible on property type, which matters here. A house with some land will usually finance conventionally where an FHA loan would struggle.
02 · Lower credit

FHA

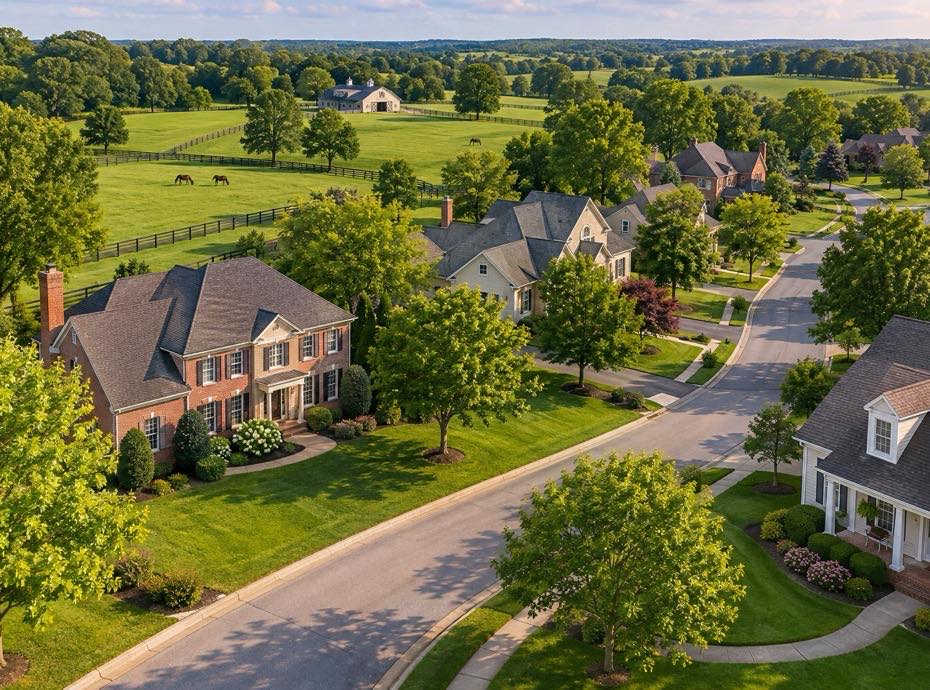
Homes backing onto horse pasture in the Bluegrass

3.5% down with more forgiving credit guidelines, up to the county limit. The trade is mortgage insurance that generally stays for the life of the loan, so it suits buyers who expect to refinance or move within a few years more than it suits buyers who plan to stay put for thirty.

FHA also applies stricter property-condition standards, which is worth knowing before you make an offer on an older house.

03 · Veterans

VA

A veteran couple we helped buy a home

Zero down, no monthly mortgage insurance, competitive rates, and no loan ceiling at full entitlement. If you are eligible it is almost always the strongest option available to you.

As with FHA, property-condition standards are stricter, so on a rural property the well, septic and access all get looked at closely.

04 · Zero down

USDA Rural Development

A rural Kentucky home

The most underused program in central Kentucky. Not available inside Lexington proper, but the eligibility boundary sits closer to the city than most buyers assume, and a great deal of the surrounding Bluegrass qualifies.

Zero down, and it is address-specific and income-limited by household size. Given how many buyers here end up looking just outside the county anyway, it is worth checking before you rule it out.

05 · Above the limit

Higher-value purchases

Buyers with the keys to a larger home

Above the conforming ceiling a loan is priced file by file rather than to a published sheet. Reserve requirements, down payment expectations and rate all genuinely differ between lenders, so comparing several is worth real money.

This is also where most horse-farm and large-acreage purchases land, and where the difference between a residential appraisal and an agricultural one starts to decide the deal.

06 · Assistance

Kentucky Housing Corporation

New homeowners celebrating their move

Down payment and closing-cost assistance for eligible buyers, with income and purchase-price limits set per county. At Lexington price points it covers a meaningful share of what you need at the table.

Not every lender is an approved KHC originator, and one who is not will simply never bring it up. If the down payment is what is standing in your way, ask explicitly.

Meet your broker

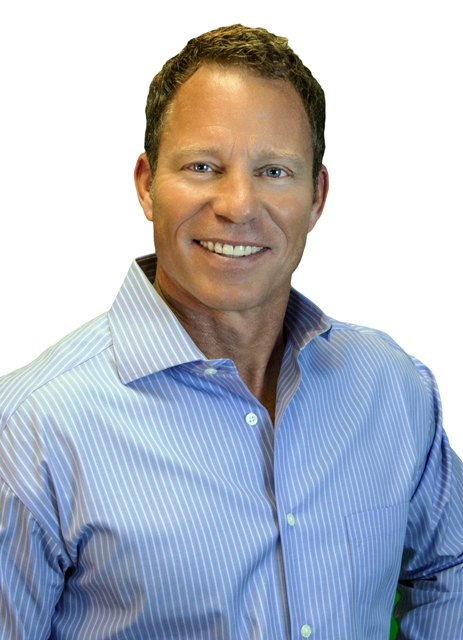
Brady Webb

Brady Webb is the President of American Mortgage Solutions. The firm started in Kentucky and still originates across the state, alongside the Southwest Florida side of the business.

Lexington rewards a broker who has seen a property with land before. A residential appraisal on twelve acres, a USDA file three miles outside the boundary and a jumbo on a horse farm are three unrelated conversations, and a lender who runs only one of them well will point you at it regardless of whether it fits.

The useful thing about working with many lenders is that an awkward property usually has an answer somewhere. Finding it is the job.

Brady Webb, President of American Mortgage Solutions
RolePresident, American Mortgage Solutions
Experience20+ years originating
LicensedFlorida, Kentucky & Indiana
NMLS#36093
Specialises inAcreage, USDA, professional contract income

Brady Webb · President, American Mortgage Solutions · NMLS #36093

Professionals meeting with their broker

A Lexington pattern

Buyers arriving from the university and hospital corridor

A large share of Lexington’s buyers arrive through UK, UK HealthCare or Baptist Health, and their files have recurring features that a general-purpose lender handles badly.

Offer letters and start dates

You can often close before your first day. Most lenders will underwrite a signed, non-contingent offer letter with a start date inside a set window — but the rules differ by lender and by how the income is structured, so it needs establishing at pre-approval rather than assumed.

Residents, fellows and physicians

Physician loan programs exist for a reason: high future income, thin current income, and student debt that a standard calculation treats harshly. The right program can discount or exclude deferred student loans and waive mortgage insurance. The wrong one declines you on debt-to-income.

Academic and research contracts

Grant-funded or fixed-term appointments raise a continuity question that catches people out. It is answerable — but the answer depends on documentation you want to gather early rather than scramble for during underwriting.

Relocating from out of state

Buying before you have sold, timing two closings, and reconciling a Kentucky purchase against a departing market are all routine. They are simply easier when the plan exists in advance.

The process

Start to finish

Buyers working through the process with their broker

Pre-approval 1–2 days

Income, assets, credit and goals. You leave knowing a real number rather than an estimate, and knowing which programs are actually open to you.

Shopping As long as it takes

Send us anything you are seriously considering, particularly if it has land attached. Five minutes now is cheaper than an appraisal surprise later.

Application and offer Same week

Under contract, we lock the file down: disclosures out, appraisal ordered, title opened.

Processing & underwriting 2–3 weeks

Verification, appraisal review, and conditions. Anything the underwriter asks for, we chase — you should not be the one collecting documents.

Clear to close ~1 week out

Final approval and the closing disclosure. Numbers confirmed, no surprises at the table.

Closing 30–45 days

Signatures and keys. Acreage and USDA files run at the longer end of that range; a straightforward in-town purchase runs at the shorter one.

Questions

Lexington
mortgage FAQ

Not in the city proper, but the eligibility boundary sits closer than most people expect and much of the surrounding Bluegrass qualifies. It is address-specific and income-limited by household size. Given how many Lexington buyers end up looking just outside the county anyway, it is worth checking a specific address before assuming it is out.

Mostly through the appraisal. A residential appraisal values a house and a typical home site; land and outbuildings beyond that frequently contribute much less than they cost. Past a certain point the property stops being residential-with-acreage and becomes agricultural, which changes the product entirely. Send us the listing before you offer.

It depends where the property sits on the residential-to-agricultural line. A house on a few acres with a barn generally finances conventionally. A working operation with income, staff and substantial acreage is a different product, and often a portfolio or Farm Credit lender rather than a conventional one. We will tell you which you are looking at.

Fayette County sits at the national FHA floor, $541,287 for 2026, against a conforming limit of $832,750. That gap is wide enough that very few Lexington purchases are constrained by it — but if you are shopping above the FHA figure, conventional is the route.

No, but it is a documentation exercise rather than a formality. Lenders generally want two years of returns and will average the income, which can understate what you actually earn if you write a lot off. Bank-statement programs exist for exactly this case, and lenders differ substantially on how they treat it. That variance is the whole argument for a broker.

Get their offer, then let us price it against the market. Builder incentives are sometimes genuinely good and sometimes a credit that costs more in rate than it returns at closing. You are not obliged to use them to keep the incentive on the table in most cases — read the wording, and let us compare the two side by side.

Get started

Send us an address, a listing, or just a rough idea of what you are looking for. If it has land attached, send it sooner — that is the one where an early answer saves the most.

Serving Lexington, Nicholasville, Georgetown, Versailles, Winchester, Richmond, Paris and the surrounding Bluegrass counties.

American Mortgage Solutions follows all Equal Housing laws. As prohibited by federal law, we do not engage in business practices that discriminate on the basis of race, color, religion, national origin, sex, marital status, age, because all or part of your income may be derived from any public assistance program, or because you have, in good faith, exercised any right under the Consumer Credit Protection Act. Disclaimer: Programs subject to change without notice. All borrowers must qualify per program guidelines.

These materials are not from HUD, FHA, the USDA, or the VA. These materials were not approved by any government agency. They are independent of any government agency. We are not in any way affiliated with any organization listed or referenced within this website, including HUD/FHA/USDA/VA. The inclusion of various education, information, web links, or materials are not an endorsement of the Sender or any of its employees or business partners. For information directly from HUD/FHA, visit https://www.hud.gov/guidance For information directly from the VA, visit http://www.benefits.va.gov/HOMELOANS/ For information directly from the USDA, visit http://www.usda.gov/wps/portal/usda/usdahome?navid=GRANTS_LOANS