Shelbyville · Shelby County, KY

In a market this size, who actually handles your file decides how it goes.

1

One point of contact from the first conversation to the closing table. Not a call centre, not a hand-off to a processing team three states away who has never heard of Shelbyville.

The market here is small, and that cuts both ways. Shelby County has few enough transactions that appraisals get unpredictable, well and septic testing takes real time, and knowing which local appraiser drew your file is genuinely useful knowledge.

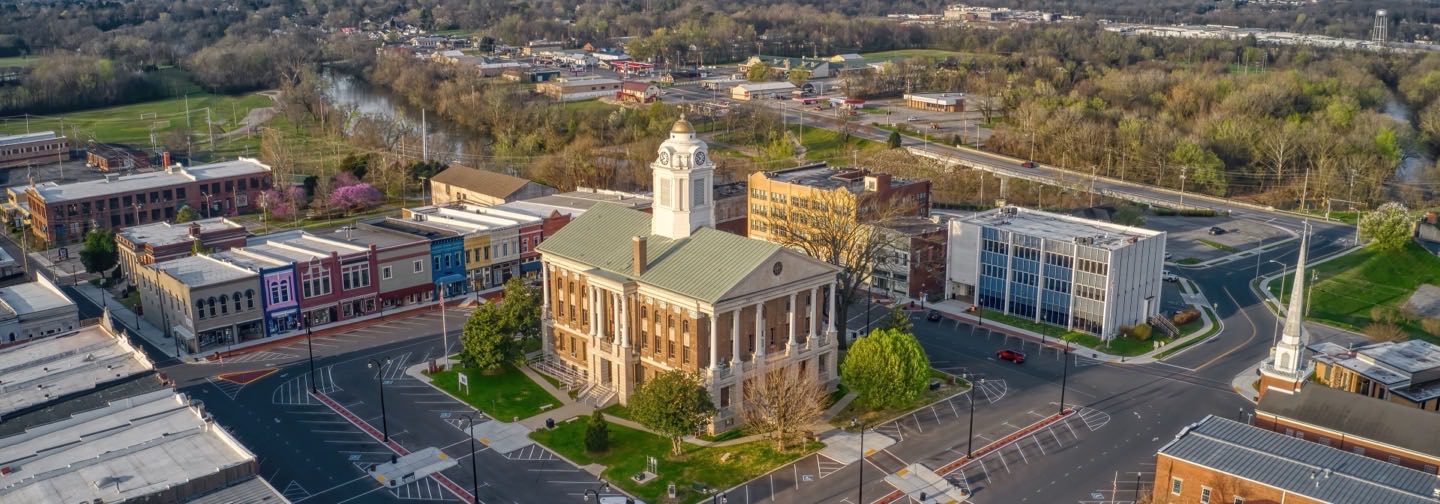
Downtown Shelbyville and the Shelby County courthouse from above

5-Star Service, Proven Results

Five-star rated on Google, Facebook, Zillow and realtor.com; BBB Accredited Business A+

Who you work with

Work directly with Brady Webb

In a market like Shelbyville’s, who handles your loan matters more than it does here. There is no volume advantage to hide behind — either your loan officer answers the phone and knows the local appraisers and closing attorneys, or your closing gets harder.

Brady Webb is the President of American Mortgage Solutions and has been originating mortgages across Kentucky for more than twenty years. Shelby County sits squarely in the territory the firm has worked longest: that is not a distinction between Louisville and Frankfort, where buyers are a mix of Louisville commuters, long-time local families, and people buying a few acres outside town.

RolePresident, American Mortgage Solutions
Experience20+ years originating
LicensedFlorida, Kentucky & Indiana
NMLS#36093
Specialises inAcreage, self-employed, rural financing
Brady Webb, President of American Mortgage Solutions

You work with Brady’s team directly, not a call centre

It is also why American Mortgage Solutions is an independent broker rather than a bank: when a file needs a lender that handles acreage well, or a self-employment set, or a zero-down program, we can send it to one.

The AMS team at work

Questions

Buying and financing in a small Kentucky market

Often far less than people assume, and for some Shelby County buyers the answer is nothing at all. Zero-down financing exists for eligible veterans, and separately for properties in areas designated rural — a designation based on population thresholds rather than how remote somewhere feels, which means much of the county qualifies and portions of Shelbyville itself may.

Beyond that, low-down-payment options start around 3% for qualified buyers, and Kentucky Housing Corporation assistance can cover part of the down payment or closing costs for those who meet its income and price limits. Which of these is best for you depends on your credit, your income and the property. It is a ten-minute conversation, and worth having before you assume you need to save for another two years.

This is the real risk in a market this size. Fewer transactions means fewer comparable sales, and an appraiser working from thin data has more room to land somewhere you did not expect. It matters most on anything unusual — acreage, an older farmhouse, a recent renovation. We flag the risk before you write rather than after the report lands.

A residential appraisal values a house and a typical home site; acreage beyond that often contributes far less than it cost, and outbuildings usually contribute close to nothing. Past a certain point the property stops being residential-with-land and becomes agricultural, which is a different product entirely. Well, septic and legal road access each add an inspection and time.

Not for the loan itself — a lender does not care where you work relative to where you live. It matters for the arithmetic though. The reason the commute pencils out for so many buyers is that Shelby County carries more cheaply than Jefferson, and that difference is worth quantifying properly before you decide.

It is a documentation exercise, not a barrier. Lenders generally want two years and will average it, which can understate what you actually earn if you write a lot off. Bank-statement programs exist for this case and lenders differ substantially in how they treat seasonal and variable income — which is exactly the variance a broker is useful for.

Thirty to forty-five days for a straightforward purchase. Add time for anything on well and septic, because the testing has its own schedule and cannot be rushed at the end. Rural and acreage files sit at the longer end of that range as a rule.

Cost of carry

What a Shelby County home costs to hold

Shelby County carries one of the lower effective tax rates in this part of the state, and insurance is modest. That combination is a large part of why the commute from here to Louisville pencils out for so many buyers.

Estimated monthly payment

$2,174/mo

Principal & interest$1,763/mo
Property tax$235/mo
Insurance$175/mo
Dues & assessments$0/mo
$

Assumptions — edit any of these

%
%
$
$
%

19% of this payment is not loan repayment. $410 a month goes to taxes and insurance — a smaller share than almost anywhere we lend, and the reason the same income buys more house here than it does in Jefferson County.

This is an illustration, not an offer. Your own rate, taxes and insurance premium will differ, and mortgage insurance is not included. On a property with well and septic, add maintenance that no escrow account covers.

Options

How buyers here typically finance

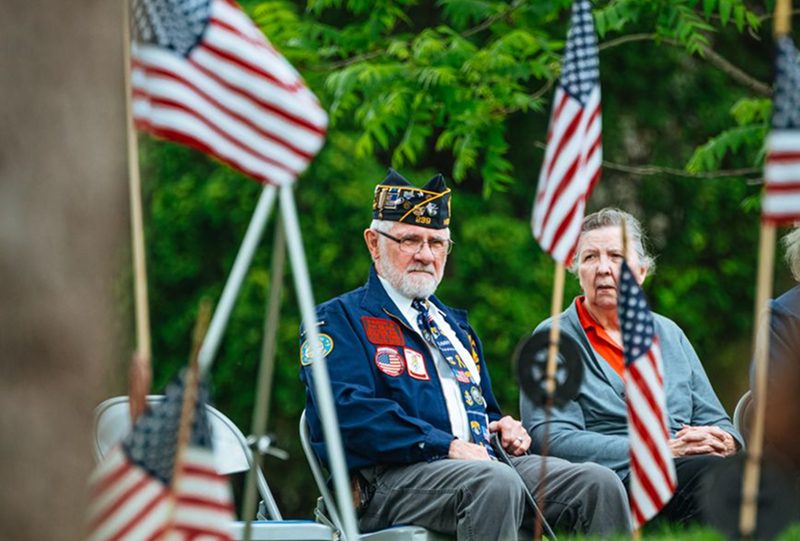
A veteran family at home

Veterans’ financing

Eligible veterans and service members buy with zero down, no monthly mortgage insurance and competitive rates, with no loan ceiling at full entitlement. Kentucky has a substantial veteran population and this is the single strongest option on the list for anyone who qualifies.

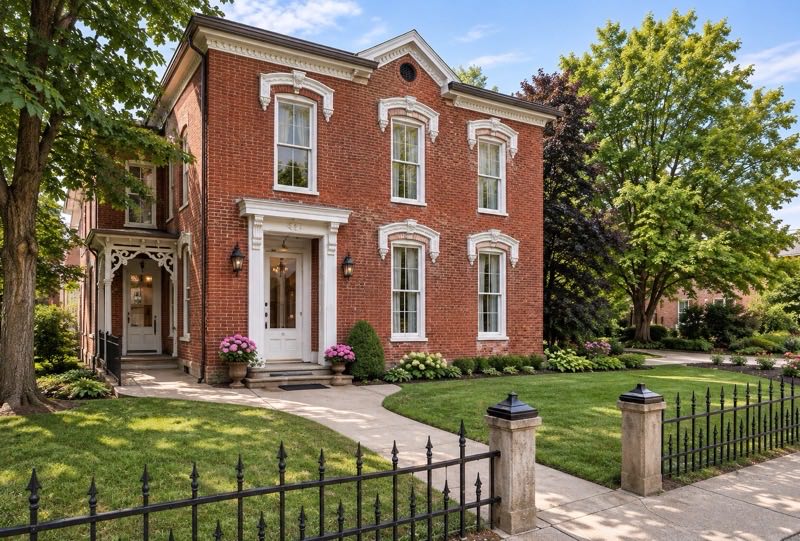
A historic brick home on a tree-lined street

Conventional

3% down for qualified first-time buyers, 5% otherwise, and mortgage insurance that comes off once you reach sufficient equity. It is also the most flexible on property type, which matters on anything with land attached.

A family moving into their new home

FHA

3.5% down with more forgiving credit guidelines, up to the county limit. The trade is mortgage insurance that generally stays for the life of the loan, and stricter property-condition standards on older houses.

Buyers holding the keys outside their new home

State assistance

Kentucky Housing Corporation offers down payment and closing-cost assistance to buyers who meet its income and purchase-price limits. Not every lender is an approved originator, so it is worth asking for by name rather than waiting to be offered it.

Reviewing building plans

Building or renovating

Shelby County has a fair amount of older housing and a fair amount of open land. Construction-to-permanent financing and renovation loans both exist to fund the work alongside the purchase, sized against the finished value rather than the current one.

Going through paperwork with a lender

Refinance

Lower your rate or payment, shorten your term, remove mortgage insurance, or access equity. We show you the break-even honestly, including when the honest answer is to leave it alone.

Outside town

Buying on acreage outside Shelbyville

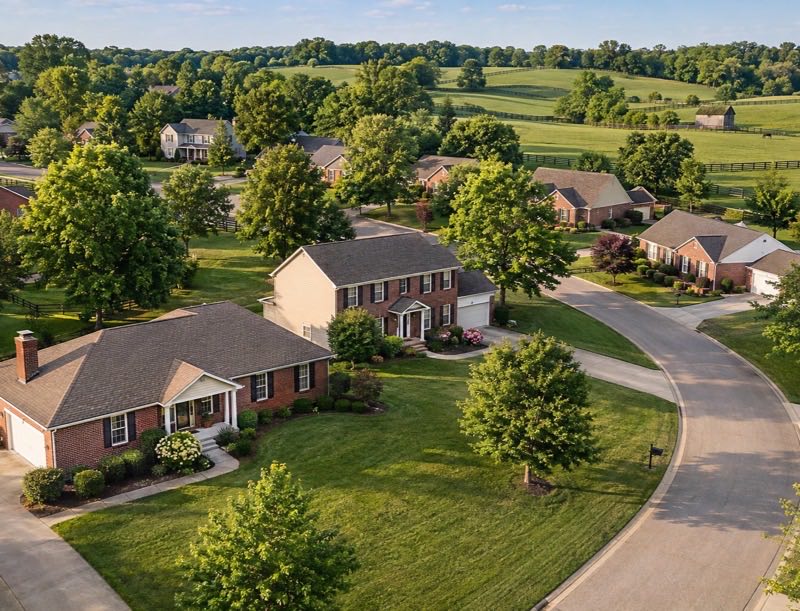
Homes on the edge of open Kentucky farmland

A lot of Shelby County purchases include land, and land changes the question.

Excess acreage often contributes far less to appraised value than the buyer expects, because residential appraisals value a house and a typical home site. Outbuildings — barns, workshops, run-in sheds — frequently receive almost nothing at all. The gap between what a property costs and what it appraises for comes out of your pocket, so it is the number worth establishing before you write.

Well and septic add inspections, each with its own scheduling and its own way of going wrong late in the file. Legal road access matters too: a shared or unrecorded driveway easement is a genuine underwriting problem rather than a formality.

And there is a line past which a property is agricultural rather than residential, at which point conventional mortgage programs stop applying and Farm Credit financing becomes the right route. If a property you are considering is near that line, we will tell you which side it is on before you are under contract.

Client experience

What Shelby County clients say

★★★★★

Highly recommend

“Brady and his team are detail oriented and work to make sure the realtor and client have the best experience. They help train realtors to be more effective and grow their business and they help homebuyers find the best programs and qualify for the best rates.”
SC
Stephanie ClementsKentucky

★★★★★

Extremely professional

“Brady and the AMS team worked efficiently and effectively with my family and I to purchase our first home. Extremely professional group that I would recommend to anyone in the market for a home.”
TP
Tyler PhillipsKentucky

★★★★★

Can’t thank them enough

“Brady Webb and Matt were fantastic to work with! They were very patient with me, as my loan situation was complicated and took some time to finalize! Throughout the entire process Matt was with me all the way to explain my best course of action.”
KL
Karen LambKentucky

Start with a phone call

Send us an address and a rough sense of your income. We will tell you what your realistic budget is, whether the property is likely to appraise, and which financing routes are open to you. No application required.

Serving Shelbyville, Simpsonville, Finchville, Waddy, Bagdad, Eminence, Taylorsville and the surrounding counties.

American Mortgage Solutions follows all Equal Housing laws. As prohibited by federal law, we do not engage in business practices that discriminate on the basis of race, color, religion, national origin, sex, marital status, age, because all or part of your income may be derived from any public assistance program, or because you have, in good faith, exercised any right under the Consumer Credit Protection Act. Disclaimer: Programs subject to change without notice. All borrowers must qualify per program guidelines.

These materials are not from HUD, FHA, the USDA, or the VA. These materials were not approved by any government agency. They are independent of any government agency. We are not in any way affiliated with any organization listed or referenced within this website, including HUD/FHA/USDA/VA. The inclusion of various education, information, web links, or materials are not an endorsement of the Sender or any of its employees or business partners. For information directly from HUD/FHA, visit https://www.hud.gov/guidance For information directly from the VA, visit http://www.benefits.va.gov/HOMELOANS/ For information directly from the USDA, visit http://www.usda.gov/wps/portal/usda/usdahome?navid=GRANTS_LOANS