Louisville · Jefferson County, KY

The mortgage that works in Norton Commons is not the mortgage that works in Old Louisville.

Louisville is a city of distinct neighbourhoods with housing stock spanning a century and a half, and the financing that suits one of them can be the wrong answer two miles away. We work across all of them.

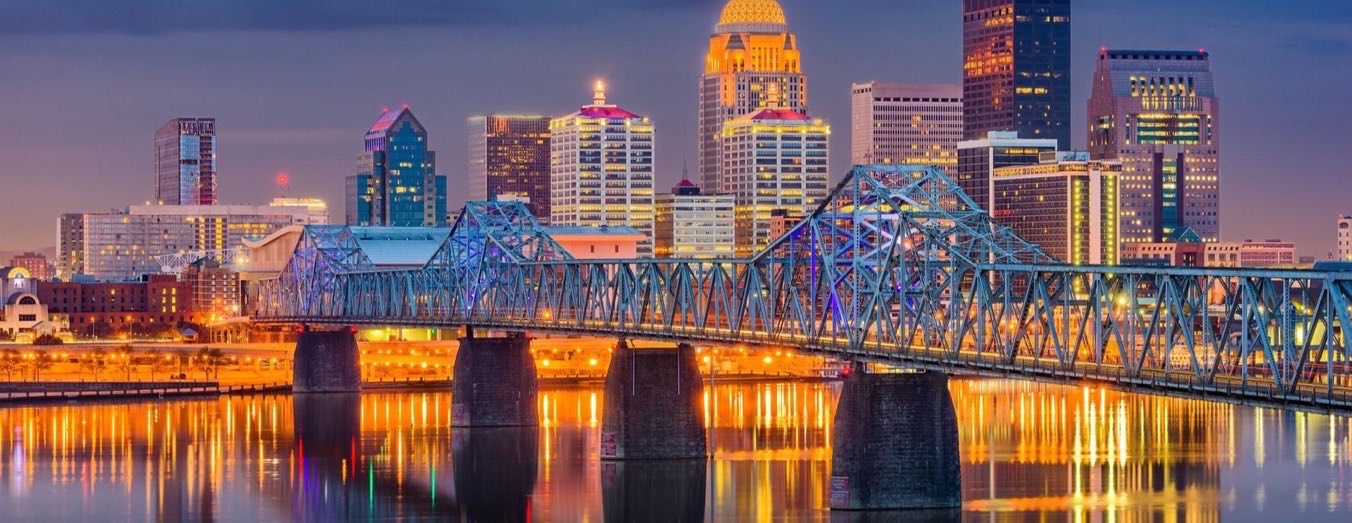
The Louisville skyline and the Ohio River bridges at night

Street by neighbourhood

Six Louisvilles, six sets of considerations

Historic core · pre-1930

Old Louisville, Butchertown & Portland
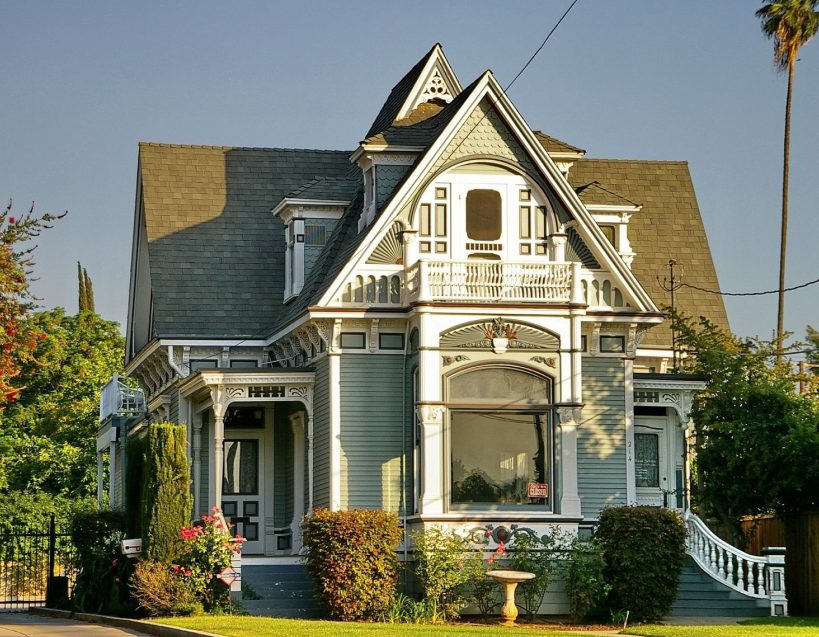
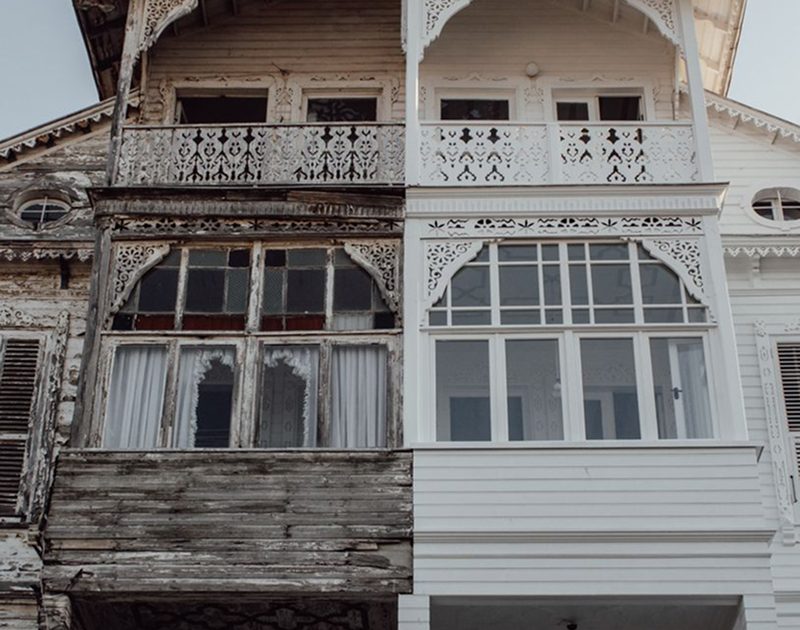
A Victorian home in Old Louisville

One of the largest Victorian districts in the country, and the financing considerations come with the architecture. Knob-and-tube wiring, original slate or tile roofs, plaster over lath, and systems that were state of the art in 1895.

What matters for your loan is property condition. FHA and VA appraisers hold stricter standards here and will call out peeling paint on a pre-1978 house as a required repair, because it is treated as a lead hazard. Conventional financing is generally more forgiving, but the appraiser still has to be satisfied the house is safe, sound and sanitary.

The upside is real. These houses are often priced well below what the same square footage costs in the East End, and a renovation loan can finance the work that brings one back rather than leaving you to fund it out of pocket.
Streetcar belt · 1900–1940

The Highlands, Germantown, Clifton & Crescent Hill

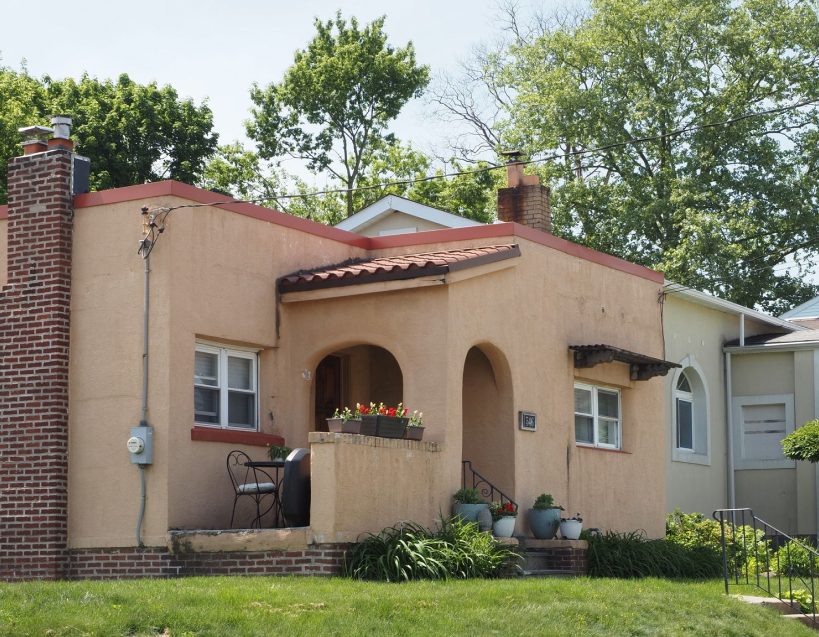
A shotgun cottage in the Highlands

Shotguns, camelbacks and bungalows on tight lots, and the most competitive inventory in the city. Houses here move fast and frequently attract multiple offers.

What matters for your loan is speed and certainty. A pre-approval that has actually been underwritten, rather than issued off a soft credit pull, is worth more than it sounds when a seller is choosing between three offers on the same Saturday.

Condition varies enormously street to street. A renovated Highlands bungalow and an untouched one can sit two doors apart and need completely different loans.

Post-war & established · 1950–1990

St. Matthews, Middletown & the East End

An established East End home

Ranches, colonials and later subdivisions, generally in good repair and the most straightforward stock in Jefferson County to finance.

What matters for your loan here is price point rather than condition. A good deal of the East End sits at the upper end of what conventional financing reaches comfortably, and above the conforming limit a loan is priced file by file rather than to a published sheet.

If you are moving up from a first house, the question worth asking early is whether you need to sell before you buy — and whether the numbers support carrying both for a short window.

Suburban south & east

Jeffersontown, Fern Creek, Okolona & Valley Station

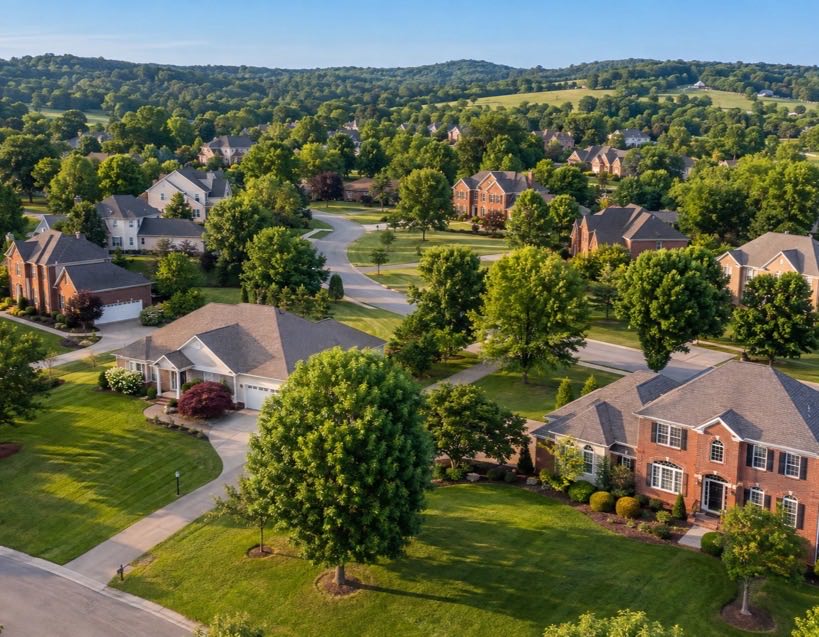
A wooded Kentucky suburb from above

Where most of Louisville’s first-time buyers actually buy. Accessible price points, sound houses, and the widest range of programs available anywhere in the county.

What matters for your loan is choosing well between them. FHA is not automatically the right answer — plenty of buyers who assume it is qualify for a 3% down conventional loan with cheaper long-run mortgage insurance. Some addresses at the outer edge of the county also qualify for USDA zero-down financing, which is worth checking before you rule it out.

Kentucky Housing Corporation assistance reaches furthest in exactly this price range.

West Louisville

Shively, Shawnee, Russell & West Louisville

A home in west Louisville

The most accessible price points in Jefferson County, and the area where the gap between a house’s purchase price and its condition is widest.

What matters for your loan is the appraisal and the repair list. On a low-priced house a required repair is a larger share of the deal, and a renovation loan — which funds the purchase and the work together, sized against the finished value — is frequently the difference between a workable purchase and a dead one.

Down payment assistance also goes further here than anywhere else in the county, simply because the numbers are smaller.

The county line

Prospect & the Jefferson–Oldham line

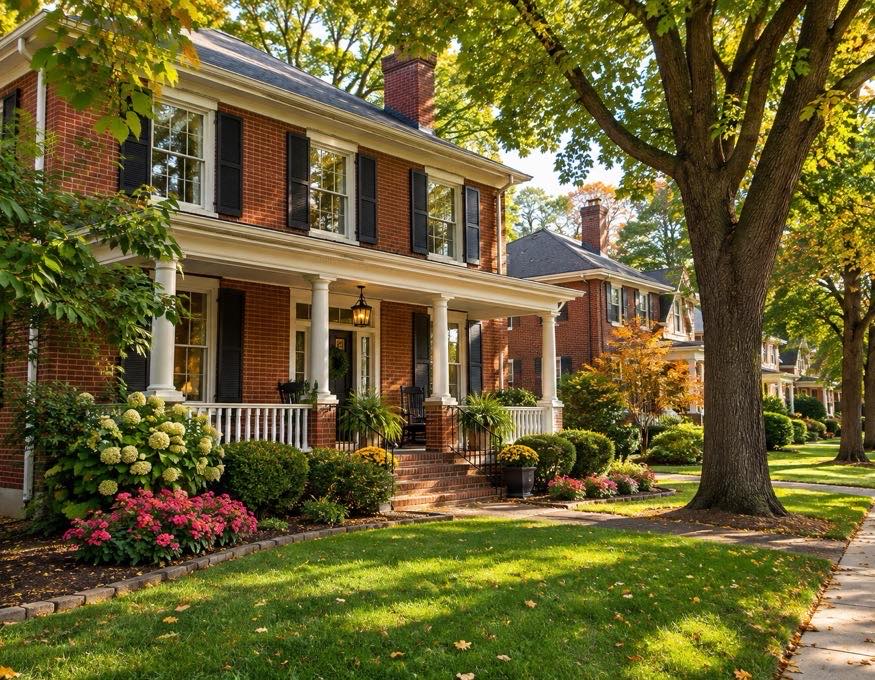
A brick home with a covered porch on a shaded street

Newer construction, larger lots, and addresses that sit on one side or the other of a county boundary that changes more than the postcode.

What matters for your loan is which county the address is actually in. Loan limits, tax rates and school districts all follow the line, and buyers regularly assume a Prospect address is in Oldham County when it is not, or the reverse. We check it before it matters.

New construction here also runs to the builder’s schedule rather than yours, so the financing needs lining up against their timeline early.

Buyers planning a renovation

The Louisville-specific tool

Renovation loans

In a city where a great deal of the housing stock predates the Second World War, the most useful loan in Louisville is often the one most buyers have never heard of.

FHA 203(k)

Purchase and repairs in one loan

Finances the purchase plus the renovation on a single FHA loan, with the amount based on what the house will be worth once the work is finished. Lower credit thresholds than the conventional equivalent, and the most common route for a first house that needs real work.

Fannie Mae HomeStyle

The conventional equivalent

The same principle on conventional terms: one loan, as-completed value, no second closing. Generally more flexible on the type of work allowed, and it drops mortgage insurance once you reach sufficient equity — which 203(k) does not.

You can buy a Highlands house that needs sixty thousand dollars of work with one loan based on the home’s as-completed value — rather than buying it, then finding the cash, then living in a construction site for two years.

A restored entrance on an older Louisville home

What to know going in

  • Contractors must be licensed and approved by the lender. You generally cannot do the work yourself.
  • Funds are held in escrow and released in draws as the work is inspected.
  • The timeline runs longer than a standard purchase — budget for it.
  • The appraisal is done on plans and specifications, not on the house as it stands today.
  • Larger projects require a consultant. A broker who has run these before is the difference between a smooth draw schedule and a stalled one.

Down payment help

Kentucky Housing Corporation assistance

First-time buyers receiving keys to their new home

Kentucky Housing Corporation offers down payment and closing-cost assistance to eligible buyers, and it is one of the more genuinely useful state programs in the country — particularly at Louisville price points, where a few thousand dollars of assistance covers a real share of what you need at the table.

Eligibility turns on income limits, purchase price limits, credit thresholds and a homebuyer education requirement, and the limits vary by county and by household size. Assistance generally comes as a second mortgage alongside your first, with terms that depend on which programme you qualify for.

It is worth checking even if you assume you earn too much. The income limits are higher than most buyers expect, and they are set per county rather than nationally.

The Kentucky catch

Not every lender is an approved KHC originator, and a lender who is not simply will not mention the programme — not out of bad faith, but because it is not on their shelf. If down payment is the thing standing between you and a purchase, ask the question explicitly rather than waiting to be offered it.

Cost of carry

What a Louisville home costs to hold

Purchase price

$

Kentucky carries a good deal more cheaply than Florida — no windstorm exposure, lower insurance, and property taxes that behave predictably. The figure below is what the house actually costs you each month.

Assumptions — edit any of these

%
%
%
$
$

Estimated monthly cost to hold

$2,090/mo

Principal & interest$1,711/mo
Property tax$216/mo
Insurance$163/mo
Dues & assessments$0/mo

18% of this payment is not loan repayment. $379 a month goes to taxes and insurance — a far smaller share than the same calculation produces in Southwest Florida, which is most of why the same income buys a great deal more house here.

This is an illustration, not an offer. Figures are built from the assumptions above; your own rate, taxes and insurance premium will differ. Mortgage insurance and closing costs are not included, and at 5% down conventional mortgage insurance would be added until you reach sufficient equity.

Client experience

What Louisville clients say

American Mortgage Solutions has been originating in Kentucky for two decades. These are from the Louisville side of the business.

★★★★★

Highly recommend

“Brady and his team are detail oriented and work to make sure the realtor and client have the best experience. They help train realtors to be more effective and grow their business and they help homebuyers find the best programs and qualify for the best rates.”
SC
Stephanie ClementsKentucky

★★★★★

Extremely professional

“Brady and the AMS team worked efficiently and effectively with my family and I to purchase our first home. Extremely professional group that I would recommend to anyone in the market for a home.”
TP
Tyler PhillipsKentucky

★★★★★

Can’t thank them enough

“Brady Webb and Matt were fantastic to work with! They were very patient with me, as my loan situation was complicated and took some time to finalize! Throughout the entire process Matt was with me all the way to explain my best course of action.”
KL
Karen LambKentucky
Brady Webb, President of American Mortgage Solutions
RolePresident, American Mortgage Solutions
Experience20+ years originating
LicensedFlorida, Kentucky & Indiana
NMLS#36093
Specialises inRenovation lending, first-time buyers, KHC assistance

Meet your broker

Brady Webb

Brady Webb is the President of American Mortgage Solutions, which has offices in Louisville and in Cape Coral, Florida. He has been originating loans for more than twenty years, and Kentucky is where the firm started.

Louisville rewards knowing the housing stock. A renovation loan on a Portland shotgun, a Kentucky Housing Corporation second on a Valley Station first purchase, and a jumbo in Prospect are three different conversations, and a lender who only runs one of them well will steer you toward it whether or not it fits.

Working with many lenders means the answer to an awkward file is usually a different lender rather than a decline. That matters more in a city with this much pre-war housing than it does in most places.

Questions

Louisville
mortgage FAQ

Rates run slightly above a standard purchase loan, and there are additional costs a normal purchase does not carry: the as-completed appraisal, inspections at each draw, and a consultant fee on larger projects. Against that, you are financing work you would otherwise pay for in cash at a much higher effective cost. On a house that needs real work it is almost always the cheaper route.

Yes, and it is routine. The thing to plan for is property condition rather than age. On a pre-1978 house, FHA and VA appraisers treat peeling paint as a lead hazard and will require it addressed before closing. Conventional financing is more forgiving, and a renovation loan can simply fund the work as part of the purchase.

Possibly, and it is worth asking even if you assume you earn too much. Eligibility turns on income limits, purchase price limits, credit and a homebuyer education requirement, and the income limits are set per county and per household size rather than nationally. Note that not every lender is an approved KHC originator — one who is not will simply never raise it.

It depends on your credit and how long you plan to stay. FHA is more forgiving on credit and allows 3.5% down; conventional can go to 3% down for qualified first-time buyers and drops mortgage insurance once you reach sufficient equity, where FHA generally does not. Plenty of Louisville buyers who assume FHA is their only option are better served by conventional. We run both before you choose.

Thirty to forty-five days for a standard purchase. A renovation loan runs longer, because the scope of work, the as-completed appraisal and the contractor approval all have to be in place before closing. Start those conversations before you are under contract rather than after.

We lend across Kentucky, and buyers looking at Oldham, Bullitt, Shelby and Spencer counties are common. County matters more than you would expect: loan limits, tax rates, KHC purchase-price limits and USDA eligibility all follow the boundary. We check which side an address falls on before it becomes a problem.

Start with a conversation, not an application

Tell us roughly what you are considering and where you are looking. We will tell you what is realistic, which programs actually fit, and whether a renovation loan or KHC assistance changes the answer.

Serving Louisville, St. Matthews, Jeffersontown, Middletown, Fern Creek, Okolona, Valley Station, Shively, Prospect and all of Jefferson County.

American Mortgage Solutions follows all Equal Housing laws. As prohibited by federal law, we do not engage in business practices that discriminate on the basis of race, color, religion, national origin, sex, marital status, age, because all or part of your income may be derived from any public assistance program, or because you have, in good faith, exercised any right under the Consumer Credit Protection Act. Disclaimer: Programs subject to change without notice. All borrowers must qualify per program guidelines.

These materials are not from HUD, FHA, the USDA, or the VA. These materials were not approved by any government agency. They are independent of any government agency. We are not in any way affiliated with any organization listed or referenced within this website, including HUD/FHA/USDA/VA. The inclusion of various education, information, web links, or materials are not an endorsement of the Sender or any of its employees or business partners. For information directly from HUD/FHA, visit https://www.hud.gov/guidance For information directly from the VA, visit http://www.benefits.va.gov/HOMELOANS/ For information directly from the USDA, visit http://www.usda.gov/wps/portal/usda/usdahome?navid=GRANTS_LOANS